
China EV Price War Fears Grow After Weak July Deliveries
China's premium EV makers Xpeng, Nio and Li Auto posted July delivery declines, reviving price war fears in the world's largest EV market. BYD defied the gloom with a 21.8% sales jump while NEV retail penetration hit a record 65.7%, as weak demand and surging battery costs squeeze margins.
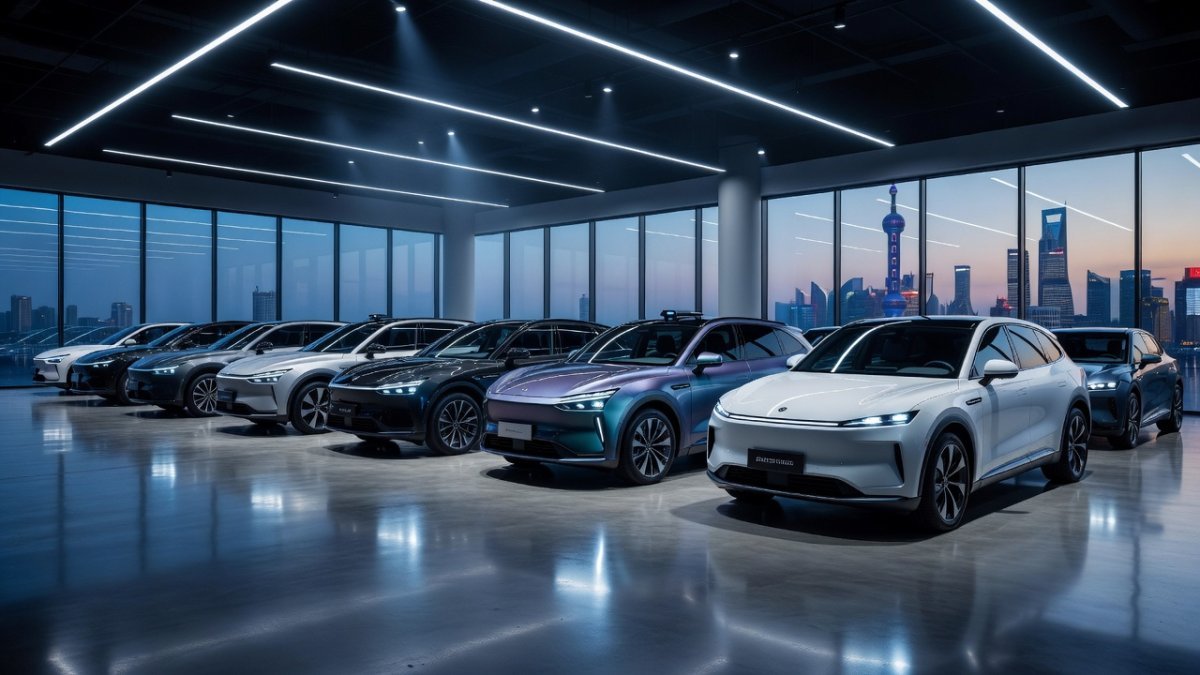
China EV Price War Fears Grow After Weak July Deliveries
Shanghai — Fears of another brutal price war are gripping China's electric vehicle market after three premium carmakers reported weak deliveries for July, the latest sign that demand for intelligent cars is cooling in the world's largest EV market. Xpeng, Nio and Li Auto all posted month-on-month sales declines, according to data published over the weekend, reviving memories of the discount battles that crushed margins across the sector in 2024.
The numbers came as the China Passenger Car Association (CPCA) reported that new energy vehicle (NEV) retail penetration hit a record 65.7 percent in the first 26 days of July, with wholesale penetration reaching 70 percent — evidence that electric cars now dominate Chinese showrooms even as the overall passenger car market contracts.
The July Delivery Scorecard
Xpeng delivered 38,027 vehicles in July, down 5.2 percent from June, ending a four-month streak of consecutive increases. Nio saw its monthly sales falter after back-to-back gains in May and June, with deliveries down 11.5 percent month on month at 35,934 units. Li Auto logged its fourth consecutive month of declining sales, with deliveries falling 1.4 percent from June to 30,468.
On an annual basis the picture is less dire. Nio's July deliveries were up 71 percent year on year, and the company has delivered 227,057 vehicles in the first seven months of 2026, an increase of 67.98 percent. Nio's ES8 sport utility vehicle topped 10,000 deliveries for a second straight month, with 10,286 units sold in July, up 14.68 percent from 8,969 in June. The divergence between month-on-month softness and year-on-year strength underscores how distorted the 2026 calendar has become: a late-2025 purchase rush pulled demand forward, and subsidy policy changes have reshaped buying patterns.
BYD Defies the Gloom
Industry leader BYD provided the counterweight, selling 419,211 NEVs at wholesale in July, up 21.76 percent year on year — the third consecutive month of annual growth — with overseas deliveries hitting a fresh record. The Shenzhen-based giant's scale advantage, vertical integration into batteries, and aggressive export push have allowed it to undercut rivals on price while still posting volume growth.
That divergence is the core of the current anxiety. While BYD can absorb margin pressure through scale, smaller premium brands with thinner order books are far more exposed to another round of discounting. Huawei's HIMA smart-car alliance delivered 45,046 vehicles in July, down 4.92 percent year on year and 11.02 percent from June — its second straight monthly decline — underscoring that even tech-backed brands are feeling the slowdown. Leapmotor and Zeekr, by contrast, reached record monthly deliveries, evidence that the market is bifurcating between winners consolidating share and mid-tier brands fighting for survival.
Why July Was Weak: Policy Timing and Seasonality
Analysts point to a mix of seasonal weakness and policy timing. July 2025 was an exceptionally strong month, distorting year-on-year comparisons, and a 2025 year-end rush pulled forward demand from early 2026 as purchase tax benefits were reduced. On a month-on-month basis, June is typically strong because of mid-year promotional campaigns, making July look worse by comparison.
CPCA preliminary data for July 1-26 shows total passenger car retail of 1.123 million units, down 18 percent year on year and 13 percent from the equivalent June period. NEV retail was 738,000 units, down just 2 percent year on year — a stark demonstration that the contraction in the overall market is being driven almost entirely by collapsing internal combustion engine sales, not by weakness in electric demand. Year to date, total passenger car retail stands at 9.824 million units, down 20 percent, while NEV retail is 5.443 million, down 13 percent.
Penetration at Record Levels
The structural shift continues to accelerate. NEV penetration rose from 5.4 percent in 2020 to 25.6 percent in 2022, 47.6 percent in 2024 and 53.9 percent in 2025, before reaching 62.8 percent in June 2026. Analysts expect the July figure to land between 65 and 66 percent once full-month data is finalized — meaning nearly two of every three new passenger cars sold in China now run on electricity.
The implications ripple far beyond China. Every incremental NEV gain is coming directly at the expense of traditional powertrains, and legacy automakers globally are feeling the squeeze. BMW reported second-quarter net profit of 1.2 billion euros ($1.4 billion), down more than a third year on year, citing intense competition in China. Mercedes has scrapped its sales and revenue forecasts after falling Chinese sales, and is pinning its hopes on a new generation of electric models. Volkswagen, Mercedes and BMW have all posted some of their worst China sales declines on record in 2026 as Chinese rivals launch premium models with the latest technology at lower prices.
Cost Pressures Threaten a New Discount Cycle
The ingredients for a fresh price war are already in place. Li Auto swung to a first-quarter loss and faces a per-vehicle cost rise of more than 14,000 yuan (about $2,060) on its next-generation L6 model, driven by surging battery and memory prices — lithium carbonate has risen roughly 200 percent while DRAM prices are up 90 to 300 percent.
At the same time, subsidy rollbacks and intensifying competition are squeezing margins across the board. Chinese EV industry growth has slowed to roughly 5 percent this year compared with 32.2 percent in the same period last year, according to industry estimates, a dramatic deceleration that has investors watching for signs of capitulation pricing among weaker players. The paradox is acute: EV makers are simultaneously fighting for share in a slowing market, absorbing higher input costs, and facing investor pressure to show a path to profitability.
Exports: The Escape Valve
Overseas markets are absorbing an ever-larger share of Chinese EV output, cushioning the domestic slowdown. Great Wall Motor sold 108,067 vehicles in July with nearly 60 percent coming from overseas — exports surged 50.93 percent year on year to 62,015 units while domestic sales fell 27.23 percent. Chery became the first Chinese automaker to export more than 200,000 vehicles in a single month, shipping 202,533 units in July, up 70.1 percent year on year. Geely's exports topped 100,000 for a second consecutive month at 106,663 units.
That export surge is reshaping global markets, pressuring European and Japanese brands in their home territories while generating the revenue needed to fund domestic price competition. It also carries geopolitical risk: the European Union's anti-subsidy tariffs and Washington's escalating restrictions on Chinese automotive technology mean the export route is not without obstacles. Chinese automakers are responding by building local factories — from Hungary to Brazil — turning exports into localized production that can bypass tariff walls.
What to Watch in August
August will be a decisive month. Denza, BYD's premium sub-brand, begins pre-sales of its Z9S sedan on August 3 with a claimed range of up to 920 kilometers, and BYD has confirmed plans to unveil a humanoid robot this month — a reminder that China's EV leaders are racing to become diversified intelligent-mobility conglomerates.
The key question is whether any major player blinks first on pricing. If a volume-hungry brand launches aggressive discounts ahead of the September-October Golden Week shopping season, the industry could slide into the kind of margin-destroying war that marked 2024. For now, the data suggests a market in transition: structurally dominant, increasingly export-driven, but acutely vulnerable to its own competitive dynamics. Investors and policymakers alike will be watching August delivery figures for the first signal of which way the market breaks.
By Kenji Tanaka, Staff Writer
SUMMARY: China's premium EV makers Xpeng, Nio and Li Auto posted July delivery declines, reviving price war fears in the world's largest EV market. BYD defied the gloom with a 21.8% sales jump while NEV retail penetration hit a record 65.7%, as weak demand and surging battery costs squeeze margins.This article was produced with AI-assisted research and editorial support. Reporting is based on sources cited in the article.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Japan Correspondent at Global1.News. Tokyo-based voice covering Japanese politics, technology, economy, and culture. Tracks the intersection of tradition and innovation in one of the world's most dynamic societies.









Comments (0)