
Hong Kong Tax Overhaul Courts Multinational Treasury Crown
Hong Kong is consulting until September 4 on a two-tier corporate treasury tax regime, with refinements and five-year pre-approval aimed at winning multinational treasury centres from Singapore and Dubai as mainland state firms hold 8 trillion yuan in overseas assets.
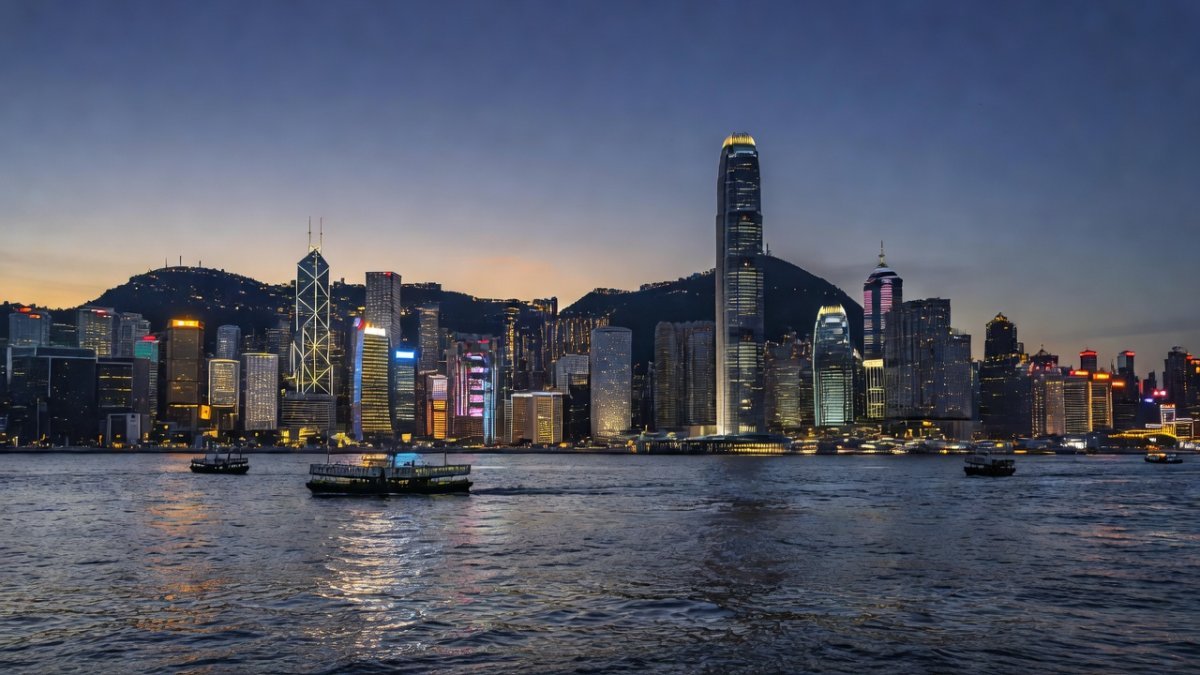
Hong Kong Opens a Two-Tier Bid for the Region's Treasury Business
Hong Kong is asking multinational groups whether a sharper tax deal can make it Asia's corporate treasury hub. On July 27, the Financial Services and the Treasury Bureau and the Inland Revenue Department launched a six-week public consultation on a two-tier tax concession regime for corporate treasury centres, with submissions closing September 4.
The proposals are not yet law. Officials have signalled that administrative clarifications on the existing regime could be issued within 2026, with amendments to the Inland Revenue Ordinance expected to reach the Legislative Council in the first half of 2027. But the strategic intent is unmistakable: Hong Kong is trying to outmanoeuvre its rivals, Singapore and Dubai above all, for the internal banking operations of the world's largest corporations.
Tags: Hong Kong tax reform, corporate treasury centre, tax consultation, Inland Revenue Ordinance, PwC, financial hub, Singapore, offshore yuan, SASAC, China SOE, multinational companies, tax incentives
A Two-Tier Design Built for Scale
Hong Kong's existing regime already gives qualifying corporate treasury centres a 50 per cent profits-tax reduction on specified treasury activities, cutting the effective rate from 16.5 per cent to 8.25 per cent. The consultation proposes keeping that foundation in a refined "Tier 1" while adding a "Tier 2" pre-approval track for the largest groups.
Tier 1 would broaden the regime's reach. Interest deductions could be expanded beyond intra-group financing to other corporate treasury activities, including cash forecasting, cash pooling and the investment of associated corporations' funds in financial instruments. The proposal would also allow interest-deduction claims to be deferred where interest is paid to a non-Hong Kong associated corporation not yet subject to tax, and it offers a worked example of a substantial-activity threshold: at least two professional staff and HK$2 million (US$254,777) in annual operating expenditure on treasury activities. Officials are also consulting on whether the current monthly intra-group financing benchmark should be averaged or removed altogether, signalling that the benchmark is guidance rather than a strict qualification rule.
Tier 2 is the more ambitious piece. It would create an Inland Revenue Department pre-approval mechanism, generally valid for five years and renewable, giving approved groups additional benefits: a 50 per cent exemption on interest income derived by a pre-approved Hong Kong associated corporation from the pre-approved treasury centre, relief from the subject-to-tax condition on qualifying interest expenses, and removal of the anti-tax arbitrage rule in exchange for an interest-expense deduction cap at 30 per cent of EBITDA. Objective conditions include group annual turnover of at least HK$100 million, treasury activities for at least six associated corporations with at least one outside Hong Kong, at least HK$4 million in annual Hong Kong operating expenditure and two professional staff. Renewal would require spending and hiring to climb by HK$1 million and one additional professional respectively in the year before renewal. The expected processing time for a complete application is six weeks.
Why an Internal Bank Is Worth Courting
A corporate treasury centre functions as an internal bank for a company operating across multiple jurisdictions. It manages group cash flows, financing, investments and risk management, and it centralises funding so that business units do not raise capital separately. That structure lets a group secure loans or bond issuance on behalf of the wider enterprise, often at lower cost, allocate capital more efficiently between subsidiaries and invest surplus cash centrally.
The economic prize is substantial. Treasury operations concentrate high-value financial activity, professional employment and international banking flows in whichever city hosts them. For Hong Kong, whose identity rests on its role as a financial intermediary for the mainland and the world, the race to keep and win those functions has become a test of competitiveness as Singapore's wealth and family-office boom draws global capital into the region.
The Singapore and Dubai Benchmark
Hong Kong is competing directly with Singapore and Dubai to attract multinationals and mainland Chinese firms to establish treasury centres. Singapore's established position as a regional treasury hub, with a broad tax-treaty network and a stable regulatory environment, has made it the default choice for many Western multinationals managing Asia-Pacific operations. Dubai has added a third pole, courting the same functions with low headline taxes and Gulf capital connectivity.
PwC tax experts argue the pre-approval mechanism is the key differentiator. "The pre-approval mechanism allows companies to obtain certainty on their tax treatment before establishing operations in Hong Kong," said Rex Ho, Asia-Pacific financial services tax leader at PwC Hong Kong. "This will substantially enhance the competitiveness of Hong Kong as a corporate treasury centre," he added, saying the city's tax regime could match those in Singapore and other major markets.
Beijing's State Giants Are Already Anchored in the City
The mainland dimension gives Hong Kong an edge no rival can fully replicate. Central state-owned enterprises now hold nearly 8 trillion yuan (US$1.1 trillion) in overseas assets across more than 180 countries and regions, spanning over 10,000 projects and entities, according to the State-owned Assets Supervision and Administration Commission. China Mobile, China Railway Rolling Stock Corp and State Power Investment have already set up treasury centres in Hong Kong, drawn by its international banking system, deep capital markets, offshore yuan pool and close links with the mainland.
That offshore yuan pool is central to the pitch. As Beijing pushes the yuan's international use, Hong Kong remains the primary offshore clearing and product hub, and treasury centres managing mainland-linked cash flows benefit from being inside that ecosystem. The consultation arrives alongside a broader government action plan, unveiled in June, to promote Hong Kong as a primary base for multinational corporate treasury centres and a platform for both "bringing in" and "going out" investment.
What Advisers and Companies Are Doing Now
Professional advisers are treating the window as urgent. "Enhancing the relevant tax incentives will not only help attract more enterprises to establish corporate treasury centres in Hong Kong, but it will also inject fresh momentum into Hong Kong's financial ecosystem," Ho said at a media briefing on Friday. Eric Gong, financial services tax partner at PwC Hong Kong, said the firm had recently hosted seminars in Shanghai and Beijing drawing hundreds of client attendees, a sign of the interest among both multinationals and mainland groups.
For companies, the September 4 deadline is a chance to shape the final design. The consultation invites feedback on the proposed thresholds, the 30 per cent EBITDA cap, the renewal escalation and the scope of qualifying activities, with submissions accepted by email or post until the close. Any changes would still need to survive the legislative process in 2027, meaning the current proposals are a roadmap rather than a finished product.
What to Watch For
Three signals will determine whether Hong Kong converts the proposal into a durable advantage. First, the government's administrative clarifications, expected within 2026, will show how aggressively the Inland Revenue Department interprets the existing regime while the bill is drafted. Second, the Legislative Council timetable in the first half of 2027 will test whether the two-tier structure survives intact, particularly the Tier 2 conditions that smaller groups have called complex. Third, the competitive response matters: Singapore has not stood still on tax competitiveness, and Japanese multinationals managing regional treasuries will be watching both cities as they review where to base Asia-Pacific cash management.
For Japan's corporate giants, the calculus is direct. Tokyo has been strengthening its own appeal as an asset-management and financial centre, but for treasury functions serving pan-Asian supply chains, the practical choice has long been Singapore or Hong Kong. A more certain, pre-approved Hong Kong regime could tip marginal decisions eastward, while a muddled outcome would hand Singapore another quiet victory. The consultation's closing date of September 4 is the moment for groups with a stake in Asia's treasury map to say so.
By Kenji Tanaka, Staff Writer
This article was produced with AI-assisted research and editorial support. Sources: South China Morning Post, Hong Kong Business Services Centre, HKSAR Government Financial Services and the Treasury Bureau.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Japan Correspondent at Global1.News. Tokyo-based voice covering Japanese politics, technology, economy, and culture. Tracks the intersection of tradition and innovation in one of the world's most dynamic societies.








Comments (0)