
DWP tells pensioners to prove they need their benefits in bid to slash 100,000 claims
The Department for Work and Pensions has begun contacting pensioners to prove their ongoing entitlement to Pension Credit, in a review expected to cut £370 million from the benefits bill by 2031 and reduce payments for up to 100,000 claimants.
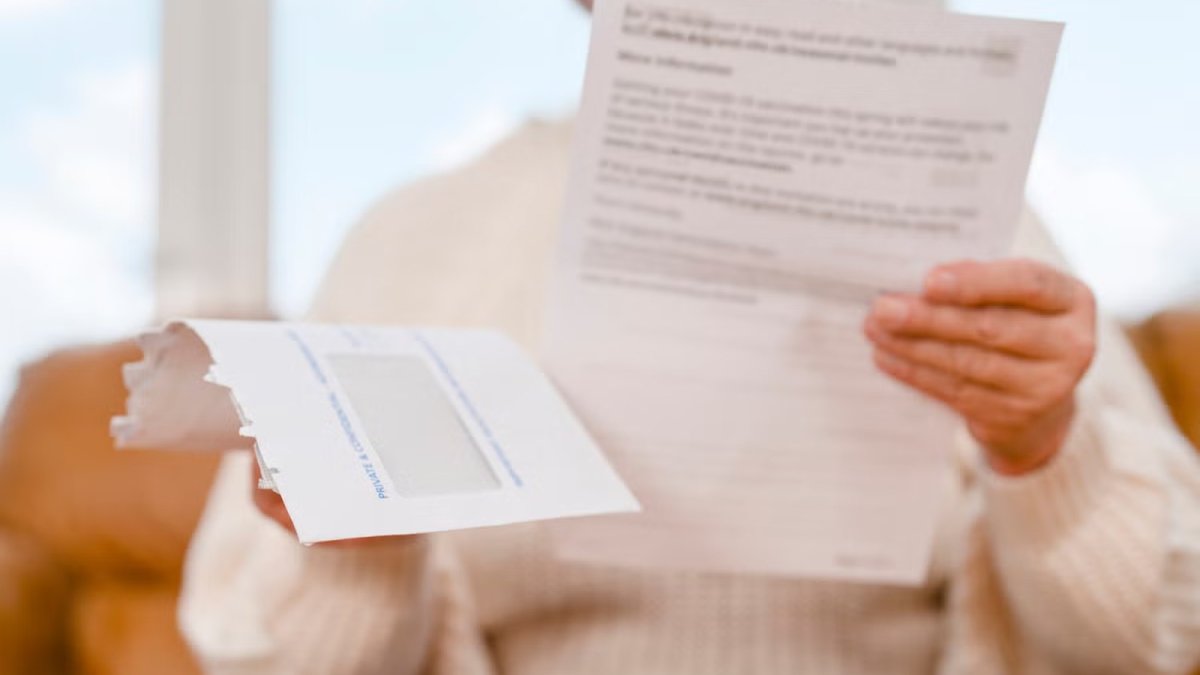
The Department for Work and Pensions has begun contacting pensioners across the country to demand they prove their ongoing entitlement to Pension Credit, in a case review designed to strip about £370 million from the benefits bill by the end of the decade.
DWP targets 100,000 pensioners in benefit clampdown
London, UK — Selected claimants are being asked to provide fresh evidence of their financial circumstances, including recent bank statements, to verify that their claims remain accurate. The review, first trailed by former chancellor Rachel Reeves at last year's Budget, is expected to result in between 95,000 and 100,000 claimants seeing their payments reduced or stopped entirely, according to estimates published by The Independent.
The drive marks a significant intensification of the government's campaign against fraud and error, targeting some of the poorest pensioners at a time when the cost of heating a home remains a live political issue. The DWP has declined to specify exactly how it is selecting cases, though it has moved to reassure those caught in the net that selection does not imply wrongdoing.
The mechanics of the review: what claimants face
For the pensioners receiving these letters, the process will be unfamiliar and, for many, intimidating. Some will need to provide additional information — which could include recent bank statements — if their case is selected for review. The DWP's messaging stresses that circumstances can change throughout the life of a claim, leading to incorrect payments; by reviewing claims, it argues, it can ensure recipients receive the correct entitlement.
The human reality is more complex. Pension Credit is a means-tested top-up designed to lift those above pension age out of poverty, boosting weekly income to £238 for single claimants or £363.25 for couples — £12,376 a year, below the full state pension and hardly lavish. The benefit also carries additional rates for those with severe disabilities, caring responsibilities, young children in their care, or certain housing costs.
The scale of the exercise is considerable. Treasury documents published alongside last year's Budget show the government expects the review to save £370 million by April 2031. This financial year alone, the DWP is set to claw back £15 million — around 10,700 claimants seeing their entitlement reduced, based on an average overpayment of £1,400. The total selected for review will likely be far higher than those ultimately sanctioned, though the DWP remains tight-lipped about selection.
A pattern of tightening: from Universal Credit to Pension Credit
This review does not exist in a vacuum. It follows a parallel and far larger drive to reduce overpayments in the Universal Credit system, a programme the government projects will save £13.6 billion by 2030. The logic is consistent: the welfare state must be leaner, more accurate, less generous to those who do not strictly qualify. But the cumulative effect on the most vulnerable households in Britain is profound.
The scale of the problem, by the DWP's own statistics, is significant. Fraud and error figures released by the department in May revealed that the proportion of Pension Credit claims overpaid rose to 33 per cent in 2025/26, up from 28 per cent the year before. The two principal causes identified were claimants under-declaring their financial assets and travelling abroad for longer periods than the rules permit. Most are administrative errors, often born of confusion or a failure to understand the reporting requirements attached to means-tested benefits.
Critics will argue the government is using a sledgehammer to crack a nut — imposing a bureaucratic burden on elderly claimants to recover relatively modest sums. The average overpayment of £1,400 pales beside the £13.6 billion being pursued through Universal Credit, yet withdrawing it from a pensioner living on £12,376 a year is disproportionately severe.
The 'passport' benefit: what is at stake
Understanding the full impact requires grasping the unique role Pension Credit plays in Britain's welfare architecture. It is frequently described as a 'passport' benefit because it unlocks a suite of additional support beyond the core payment — housing benefit, support with mortgage interest, and a free TV licence. The package can be worth up to £9,665 for the most vulnerable pensioners, a lifeline that makes the difference between a warm home and a cold one.
This is why the review carries acute risk. A pensioner who loses Pension Credit does not simply lose the top-up payment; they lose the entire ecosystem of support attached to it. The withdrawal of a free TV licence may seem a minor matter in Whitehall, but for an isolated older person the television is often their primary source of company and connection to the outside world. The cumulative loss of housing benefit could, in the worst cases, threaten a person's ability to remain in their home.
The DWP's messaging acknowledges the sensitivity of the exercise. In its update to employment groups, it emphasised that "the government wants all pensioners to get the support they are rightly entitled to." A spokesperson added: "We know that a claimant's circumstances can change throughout their claim, which can lead to their claim being incorrect. By reviewing claims, we can ensure claimants are receiving the correct entitlement."
A history of underclaiming: the paradox at the heart of the policy
There is a bitter irony in the government's decision to aggressively pursue overpayments in Pension Credit while the benefit remains chronically underclaimed. Research from Policy in Practice found that approximately 761,000 pensioners missed out on the benefit in 2025/26. Its analysis, reported by the Express last October, concluded that "four in 10 pensioners eligible for Pension Credit aren't claiming it, missing out on over £2,000 a year."
This is not a new problem. Take-up has been a long-running concern across successive governments, with awareness campaigns achieving only partial success. Last October's campaign resulted in an additional 33,500 awards, which the DWP spokesperson said were "worth on average £87 a week, compared with the previous year."
The paradox is stark: on one hand the government spends public money encouraging eligible pensioners to claim; on the other it deploys resources to strip payments from those already in receipt. The net effect on the public finances may be positive, but every pound saved is a pound removed from the household budget of a pensioner who, in most cases, believed they were claiming correctly.
The political context: Winter Fuel Payments and the cost of living
In 2024, the same administration made the contentious decision to means-test the Winter Fuel Payment, cutting it for most pensioners not in receipt of Pension Credit or other means-tested benefits — a move that provoked a significant backbench rebellion and criticism from charities.
The Pension Credit case review can be seen as the second phase of that strategy: ensuring the means-testing regime is robust enough to deliver the savings the Treasury has banked. The £370 million expected is already baked into the government's fiscal forecasts, so the DWP is under significant pressure to deliver.
Yet the political calculus is fraught. The government is asking pensioners to prove their poverty at a time when the state pension remains below the official "minimum income" standard for older people. Pension Credit exists precisely because the state pension is insufficient — it is the mechanism by which the state acknowledges that basic retirement income is inadequate. Subjecting that mechanism to aggressive review, with all the anxiety and bureaucracy it entails, is politically risky.
What happens next: uncertainty and the human cost
For the 95,000 to 100,000 claimants expected to lose some or all of their Pension Credit, the coming months will bring significant uncertainty: it is not yet clear how long the reviews will take or how appeals will be handled. Claimants who receive a letter will need to gather their financial records, respond within the specified timeframe, and hope their circumstances warrant continued support.
These are, by definition, some of the poorest pensioners in Britain — people who have worked all their lives and now find the state demanding they justify their claims. An average overpayment of £1,400 represents, for many, the difference between eating well and eating poorly, between heating the bedroom and sleeping in the cold.
The DWP's position is that accuracy in the benefits system is a public good — that ensuring claimants receive the correct entitlement is in everyone's interest. There is merit in that argument: a welfare state that tolerates significant error, whether overpayment or underpayment, is failing its core mission. But the balance between accuracy and compassion is delicate, and prioritising clawback over take-up raises uncomfortable questions about the government's priorities.
The government will point to the £370 million in savings and the need for fiscal discipline; the charities will point to the human stories, the anxiety, the cold. The truth, as ever, lies somewhere in between. But for the 100,000 pensioners facing reduced payments, the arithmetic is simple: less money, less security, and a colder winter ahead.
This article was produced with AI-assisted research and editorial support. Sources: The Independent, Policy in Practice, HM Treasury.
By Erica Thornton, Staff Writer
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
US Politics and Policy Correspondent at Global1.News. Based in Washington DC, covering American politics, policy, elections, and the courts. Knows how the system works and tells you what it actually means.









Comments (0)