
Wall Street Is Buying Gigawatts, Not Data Centers — and the Dealmakers Just Admitted It
The Bloomberg Deals panel says power and infrastructure now sit at the center of data-center dealmaking. With nVent's $1.75B Maverick Power buy and McKinsey's $7T buildout forecast, the AI trade has become an electricity trade -- here is what independents should do.
Wall Street Is Buying Gigawatts, Not Data Centers — and the Dealmakers Just Admitted It
Let me tell you something that's been sitting with me since yesterday. Three of the most serious people in the infrastructure deal business sat down on Bloomberg Television and basically said the quiet part out loud: the data center is no longer the asset being bought and sold. The power is. The land is. The grid connection is. The building full of servers is just the box it comes in.
I've been running hosting infrastructure for over a decade, and I've watched this industry go through every phase a hype cycle has to offer. But this one is different. When the lawyers and the private equity funds start describing your business as an electricity play, you need to pay attention. Because they're not describing what they wish would happen — they're describing what they're already pricing into the deals.
The Panel That Just Told You Everything
The segment was called "Power, Infrastructure At Center of Data-Center Deals," and it ran on Bloomberg Deals with Dani Burger. The guests were Maria Goodpaster, a partner at McKinsey; Kate Dorsey, a managing director at Stonepeak; and Melissa Kalka, an M&A and private equity partner at Kirkland & Ellis. That's a consulting firm, a private equity firm, and one of the biggest corporate law firms on the planet. These are not tech YouTubers riffing on a trend. These are the people who structure the transactions.
And every single one of them came to the same conclusion: the dealmaking in this sector is now organized around power and infrastructure, not around compute. It's not "how many megawatts of GPUs can we lease." It's "how many megawatts of electricity can we secure, and what does the infrastructure around it cost?" That inversion matters, because it changes who owns the value in this market.
The Deal Slate Says the Same Thing
You don't have to take the panel's word for it. Look at what actually closed in the last week. nVent Electric — the electrical company that spun out of Pentair back in 2018 — agreed to buy Maverick Power for $1.75 billion, with up to another $550 million in earnouts on top. Maverick makes power distribution gear: low- and medium-voltage switchgear, switchboards, integrated modular power solutions. It's based in McKinney, Texas. It's the biggest deal nVent has done since the spinoff, and it's the company's ninth acquisition since 2018. Bloomberg's own headline said it plainly: "nVent seeks bigger piece of AI boom with $1.75 billion deal."
That's not a chip company buying a chip company. That's an electrical equipment maker paying nearly two billion dollars to own the plumbing between the grid and the server. And nVent isn't alone. Kirkland & Ellis, one of the firms on that Bloomberg panel, just guided a $225 million data center acquisition inside a $1 billion spending plan for I Squared — and the stated reason for the price was that the facilities sit on owned real estate with existing high-density power infrastructure. Not the customers. Not the contracts. The power.
McKinsey, meanwhile, has been publishing its "$7 trillion race" analysis: roughly $5.2 trillion in capital expenditures for AI-grade data centers by 2030, plus another $1.5 trillion for traditional IT facilities. That's the consulting firm's own number, and it's the number the dealmakers are using to justify the valuations. Data Center Knowledge's own M&A outlook for the year says deal activity stays robust "despite power and AI risks" — which is a polite way of saying power is now the risk AND the reason for the deal at the same time.
Reading One: Capital Finally Priced the Right Thing
Here's the charitable reading, and I want to give it its due. For two years, the AI infrastructure market has been priced like a compute market. Every forecast led with GPUs. Every earnings call led with accelerator backlog. The power problem was treated as a footnote — something the utilities would figure out, the way they figured out every other demand surge since the 1990s.
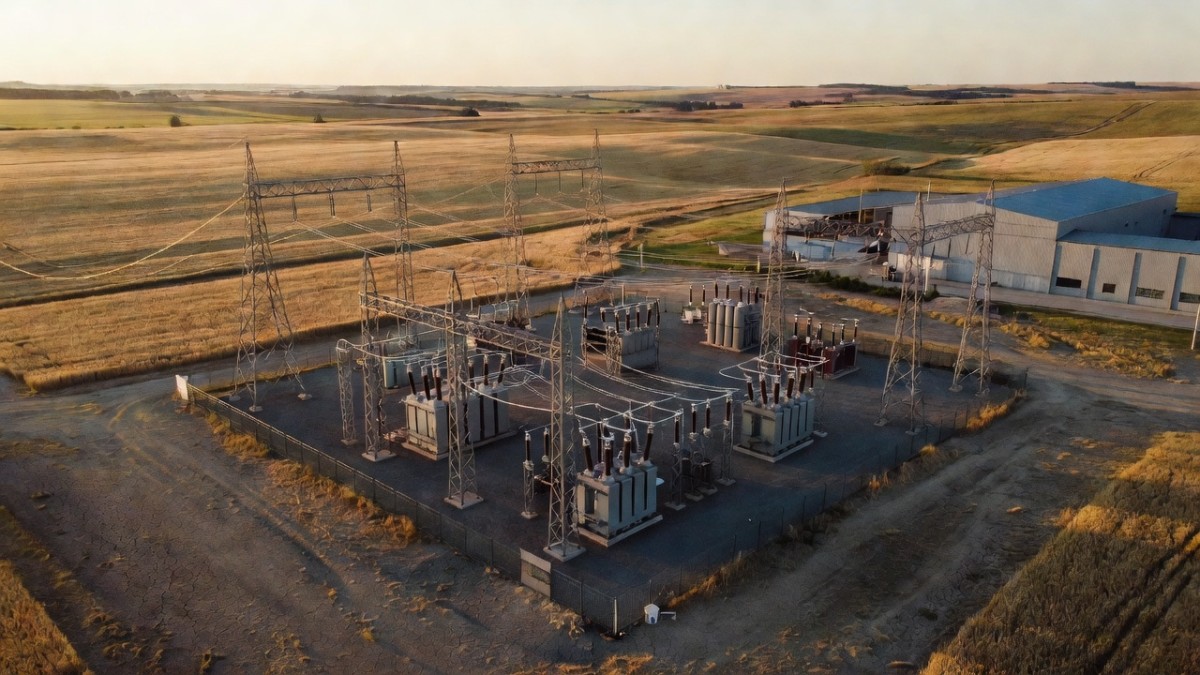
That was always wrong, and the market has finally figured it out. The physical reality is brutal: transformers with five-year lead times, interconnection queues measured in hundreds of gigawatts, grid upgrades that take a decade. If you're a private equity fund looking at a data center deal, the single biggest determinant of whether that asset is worth anything in five years is whether it can actually get the electricity. So capital is doing what capital does — it's following the constraint. Deals get priced around power availability. Acquisitions target power equipment makers. Land with existing high-density grid access trades at a premium, because it's the one thing you literally cannot build fast enough to meet demand.
That's not stupid. That's rational. When Stonepeak — an infrastructure fund with real money in real assets — puts power at the center of its thesis, they're not being clever. They're being accurate about the physics.
Reading Two: This Is How the Next Credit Cycle Gets Built
But here's the reading that keeps me up at night, and I want you to hear it too. When the dealmakers — the lawyers, the funds, the consultants — become the center of gravity of an infrastructure buildout, what you're watching is financialization. And financialization has a track record.
Think about what "power is the asset" actually means in transaction terms. It means the value isn't in operations anymore, it's in the balance sheet. It means assets get bought for their grid connection and flipped for the scarcity premium. It means the debt markets start underwriting electricity access instead of cash flow. The data center debt market was already on pace for hundreds of billions of dollars in issuance this year, with a mountain of off-balance-sheet obligations hiding behind vendor financing and lease structures. Now you're going to add a layer of M&A on top of that, where the collateral is a gigawatt connection and the multiple is whatever the scarcity narrative will bear.
I've said this before and I'll say it again: nobody ever lost money in a boom by being early to call the bubble. They lost money by being early to call the TOP. And I'm not calling a top. The demand for compute is real, the power constraint is real, and the deals being struck today are rational responses to a genuine shortage. But rational responses to a genuine shortage can still become the foundation of a credit cycle nobody planned. When the equity check clears on a $1.75 billion power equipment acquisition, that money has to be earned back somewhere down the line. The question is who earns it — and what happens to the price of electricity, colocation, and hardware when the financialized layer starts demanding its return.
What This Means for Independent Hosting Providers
First, watch who's buying power assets in your region. The nVent-Maverick deal isn't a one-off; it's the shape of things to come. When industrial equipment companies and infrastructure funds start consolidating the power distribution chain, the price of gear and the price of interconnection both move. If you're planning capacity in the next 24 months, know who owns the switchgear between you and the grid.
Second, treat your grid connection as your most valuable asset. You may think your value is your racks, your bandwidth, your support team. The dealmakers just told you otherwise. Your colo's real estate with high-density power access is exactly the asset class being bid up right now. That means two things: protect it, and don't undervalue it if someone comes knocking. But it also means the operators who control power contracts have leverage they didn't have two years ago — so read your renewal terms carefully.
Third, lock your power costs while you still can. Every dollar of financialized debt in this sector has to be repaid from somewhere, and the easiest place to collect is the rate structure — power prices, colo rates, and interconnection fees. If you're on a fixed-rate power contract, extend it. If you're on month-to-month, that's now a liability, not a convenience.
Fourth, don't confuse a healthy deal market with a healthy operating market. The M&A wave says capital wants in. It doesn't say your customers' budgets grew, or that demand at YOUR price point materialized. Financialization can inflate asset prices while the actual operating business — the one that pays bills with recurring revenue — stays flat. Keep your pricing grounded in real costs, not in the multiples you see in the deal pages.
The Bottom Line
The Bloomberg panel didn't break news. It confirmed what anyone who's actually tried to build in this market has known for two years: power is the product now. Data centers are just the delivery mechanism.
That's not a doom story. It's an accuracy story. The market is finally pricing the true constraint, and that's healthier than pretending compute grows on trees. But when the lawyers and the funds become the center of gravity of your industry, you have to remember what they're actually building: a financial asset with a gigawatt underneath it. Your job is to make sure you're not the one paying the carrying cost.
Watch the power deals. Lock the power costs. And whatever you do, don't confuse a boom in transactions with a boom in demand at your door.
— Allan Ali, Founder
This article was produced with AI-assisted research and editorial support. Sources: Bloomberg Television, Bloomberg News, McKinsey & Company, nVent Electric, Data Center Knowledge, Data Centre Magazine.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0

Publisher of Global1.News. Automation architect, systems builder, and the guy making sure the truth gets published.









Comments (0)