
Polysilicon Tariffs: Trump's New Front in the US-China Tech War Targets the Solar and AI Supply Chain
The executive order signed by President Donald Trump on Thursday marks a significant recalibration of the United States' economic statecraft, moving beyond finished goods to strike at the foundational inputs of the digital and green energy age.
The Strategic Calculus: From Export Controls to Import Tariffs
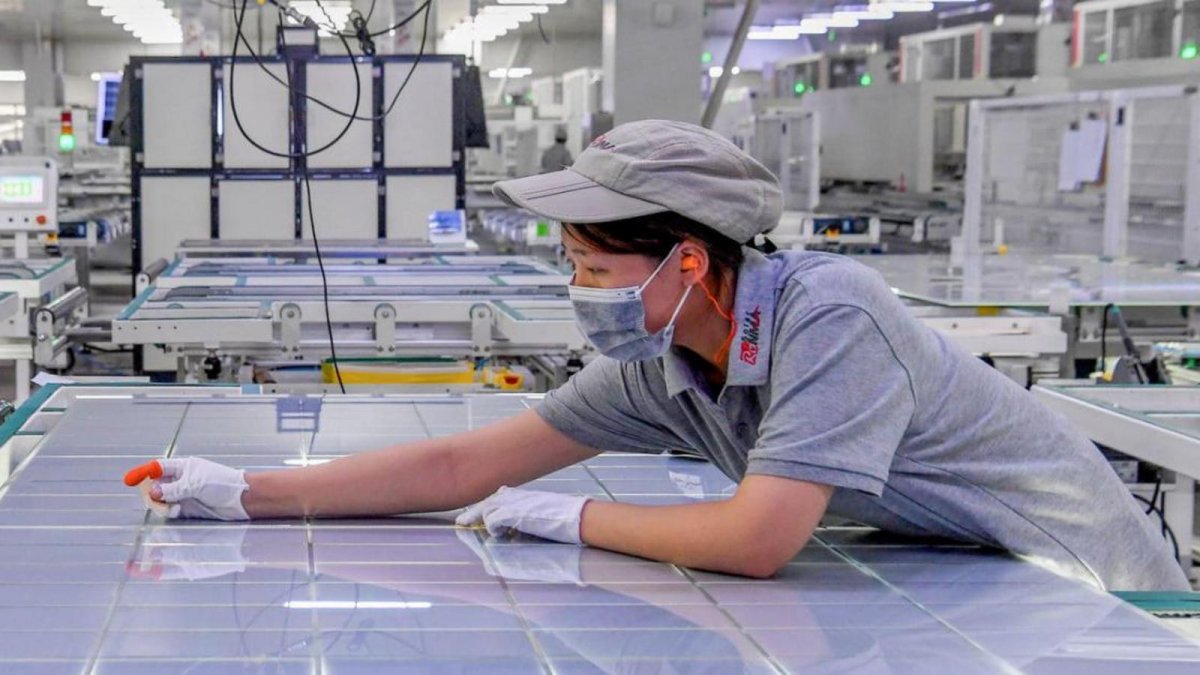
The shift in US policy from restricting high-end chip exports to taxing the raw materials of the tech economy represents a logical, albeit aggressive, escalation. For years, Washington's primary lever was the denial of advanced semiconductor manufacturing equipment to Chinese firms. However, the new tariff addresses a different vulnerability: the US's own dependence on imported polysilicon. President Trump's order explicitly frames this as a corrective measure, noting that the US share of global polysilicon production has collapsed from 50% in 2005 to less than 2% in 2024. This decline is not an accident of market forces but a consequence of deliberate industrial policy abroad and neglect at home. By invoking national security, the administration is laying the legal groundwork to treat polysilicon not as a commodity, but as a strategic asset akin to rare earths or defense-grade electronics.
The timing is critical. The tariff is due to take effect in December, a deliberate delay that provides domestic producers time to ramp up capacity and gives the market time to adjust. This is not a snap decision but a phased implementation, suggesting a calculated approach to avoid immediate supply shocks while signaling long-term intent. The acceptance of Commerce Secretary Howard Lutnick's recommendations, which include both the tariff and minimum import prices, indicates a coordinated executive branch strategy. The minimum price mechanism is particularly potent; it prevents Chinese producers from simply absorbing the tariff and undercutting US firms on price, ensuring that the cost of the trade war is borne by the exporter rather than the US treasury.
China's Response: A Firm Warning and a Pledge to Protect
The reaction from Beijing has been swift and unequivocal. The Chinese embassy in Washington issued a statement condemning the move as a "serious disruption" to bilateral trade, accusing the US of "abusing state power to go after Chinese businesses." The embassy's rhetoric, which includes the assertion that "protectionism will not make the US more competitive," reflects a deep frustration with Washington's use of national security as a catch-all justification for economic intervention. This is not the language of a party seeking negotiation; it is the language of a state preparing for retaliation. The embassy's pledge that "Beijing will act to protect its companies" is a clear promise of countermeasures, though the specific nature of those measures remains undisclosed.
This week, China has already demonstrated its capacity for calibrated response. Beijing announced tighter export controls on drones, a direct counter to US restrictions on Chinese drone imports. More significantly, China launched a national security review into imported printers and copiers, a move that mirrors the US investigation into polysilicon. This tit-for-tat dynamic, where each side uses the other's legal frameworks against them, suggests that the "truce" in the tariff war that has been in place since May 2025 is fragile. The truce may have paused the escalation on consumer goods, but it has not resolved the underlying structural conflict over technology leadership. The polysilicon tariff is a clear indication that the truce does not extend to critical infrastructure sectors.
The Domestic Winners: Hemlock and Wacker's Moment
While the tariff is a geopolitical statement, its most immediate beneficiaries are the two main US producers of polysilicon: Hemlock Semiconductor and Wacker Chemie. These companies have long struggled to compete with Chinese state-subsidized rivals that benefit from economies of scale and lower energy costs. The 15% tariff, combined with minimum import prices, creates a protective moat around their operations. For Hemlock, a Michigan-based firm, this is a lifeline that could justify new capital investment. For Wacker Chemie, a German company with a major US plant in Tennessee, the tariff aligns with its strategic interest in diversifying its production base away from Europe and Asia.
However, the benefits are not without costs. The US government has also promised incentives to boost domestic production, which will require significant fiscal outlay. The question is whether these incentives will be sufficient to rebuild a supply chain that has been hollowed out over two decades. The 2% production share is a stark indicator of how far the US has fallen. Rebuilding to even 10% or 15% of global capacity will require not just tariffs but a sustained industrial policy that addresses energy costs, skilled labor, and environmental regulations. The tariff is a necessary but insufficient condition for revival; it buys time, but it does not guarantee success.
Implications for the Solar Industry: A Double-Edged Sword
The impact on the solar industry is complex and potentially contradictory. On one hand, the tariff protects US solar panel manufacturers from cheap Chinese polysilicon, which could help them compete in the domestic market. On the other hand, it raises input costs for US solar installers and developers, who rely on imported panels to keep project costs low. This could slow the pace of the US energy transition, a goal that the administration claims to support. The minimum import price mechanism is designed to prevent a race to the bottom, but it also creates a price floor that may make solar less competitive against fossil fuels in the short term.
This tension highlights a fundamental dilemma in US policy: the desire to onshore critical supply chains versus the need to deploy clean energy rapidly. The polysilicon tariff is a bet that domestic production can be scaled up quickly enough to meet demand without derailing the solar buildout. If that bet fails, the US could face a scenario where it has protected its domestic industry but sacrificed its climate goals. The strategic calculus here is that long-term supply chain security outweighs short-term cost increases, but this is a politically risky position that will be tested in the coming years.
The AI Race and Semiconductor Supply Chains
The connection between polysilicon and the AI race is less direct but no less important. While advanced chips are made from monocrystalline silicon wafers, the broader semiconductor ecosystem relies on polysilicon for various components and substrates. More critically, the tariff is a signal of intent: the US is willing to use all tools at its disposal to secure the entire stack of technologies required for AI dominance. The production of computer chips is central to the US-China race to develop artificial intelligence, and this move demonstrates that Washington views the supply chain holistically, from raw materials to finished processors.
Analysts quoted by Chinese state media outlet Global Times have framed this as the latest escalation in Washington's efforts to limit China's role in critical technology supply chains. This is an accurate assessment. The tariff is part of a broader pattern that includes restrictions on drones, humanoid robots, and other tech products. The US is not just trying to win the AI race; it is trying to ensure that China cannot even participate on equal terms. This is a zero-sum approach that leaves little room for compromise. The Chinese response, including the national security review into printers and copiers, suggests that Beijing is prepared to play the same game, targeting US industries that are vulnerable to Chinese market power.
Global Supply Chain Repercussions: ASEAN and the EU in the Crossfire
The ripple effects of this tariff will be felt far beyond the US and China. For ASEAN countries, which have become hubs for electronics assembly, the tariff could disrupt their access to cheap polysilicon and increase the cost of their exports. Many of these nations are caught in the middle of the US-China tech war, trying to maintain neutrality while benefiting from supply chain diversification. The tariff may accelerate the trend of "China Plus One" sourcing, but it also creates uncertainty for companies that have invested in Southeast Asian production facilities based on the assumption of open trade.
For the European Union, the tariff is a double-edged sword. Wacker Chemie, a German firm, is a beneficiary, but the EU as a whole is a major importer of solar panels and polysilicon. The EU's own Green Deal industrial policy may be complicated by US protectionism, which could force European companies to choose between US and Chinese markets. The tariff also raises questions about the future of the WTO, as both the US and China are increasingly bypassing multilateral dispute resolution in favor of unilateral action. This is a worrying trend for the Global South, which relies on a rules-based trading system to protect its interests. The polysilicon tariff is a reminder that the great power competition is reshaping the global economy in ways that may leave smaller nations with fewer options.
Strategic Implications: A New Phase of Economic Warfare
The polysilicon tariff represents a new phase in US-China economic warfare, moving from the high-end of the technology stack to its foundational materials. It is a clear signal that the US is no longer content to merely restrict Chinese access to advanced technology; it is now actively seeking to rebuild its own industrial base in critical sectors. The success of this strategy is uncertain. The US has a history of protecting industries that fail to become competitive, and the 2% production share suggests a long road to recovery. However, the combination of tariffs, minimum prices, and domestic incentives creates a powerful policy cocktail that could, over time, reshape the global polysilicon market.
For Beijing, the response will be to accelerate its own self-sufficiency efforts and to find new markets for its excess polysilicon capacity. China's near-monopoly position gives it leverage, but it also makes it a target. The coming months will reveal whether the December implementation date holds and whether China's countermeasures will be proportionate or escalatory. The truce of May 2025 appears to be a distant memory, replaced by a more entrenched and structural conflict. The world is watching to see if this is a tactical maneuver or the beginning of a prolonged siege on the foundations of the digital economy.
This article was produced with AI-assisted research and editorial support. Sources: BBC News.
By Prof. Marcus Chen, Staff WriterWhat's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
World Politics Analyst at Global1.News. Based in Beijing, covering US-China relations, global trade, and geopolitical strategy. Brings deep analytical perspective to the power dynamics shaping international affairs.







Comments (0)