
Britain's Strategic Recalibration on Foreign Ownership Tests UK-China Investment Ties
Britain's Strategic Recalibration on Foreign Ownership Tests UK-China Investment Ties In the latest episode of CGTN's Observing Europe series, journalist Li Jianhua examines how iconic British assets have passed into foreign hands, from London's black cabs produced by a Geely subsidiary to Jaguar Land Rover under India's Tata Motors.
In the latest episode of CGTN's Observing Europe series, journalist Li Jianhua examines how iconic British assets have passed into foreign hands, from London's black cabs produced by a Geely subsidiary to Jaguar Land Rover under India's Tata Motors. The report highlights a broader shift: after decades of openness to global capital, Britain is reassessing which sectors remain open to overseas investors amid rising national security concerns.
This evolution carries direct implications for Chinese firms that have built significant stakes in the UK economy. Beijing's approach to overseas investment, framed within the Dual Circulation strategy, seeks stable outlets for capital while advancing technological and industrial goals. The UK's response will shape whether those channels remain viable or face new restrictions.
The Ownership Map of Modern Britain
Foreign ownership extends across Britain's most visible symbols. Geely's London Electric Vehicle Company produces the TX electric black cab in Coventry, continuing a Chinese presence in the automotive sector that began with the 2010 acquisition of Volvo. Jaguar Land Rover has operated under Tata Motors since 2008, while BMW has owned Mini since 2000. Airports, utilities, and commercial real estate show similar patterns, with independent analysis by Tax Policy Associates indicating nearly 100,000 properties in England and Wales valued at roughly 460 billion pounds held by offshore entities.
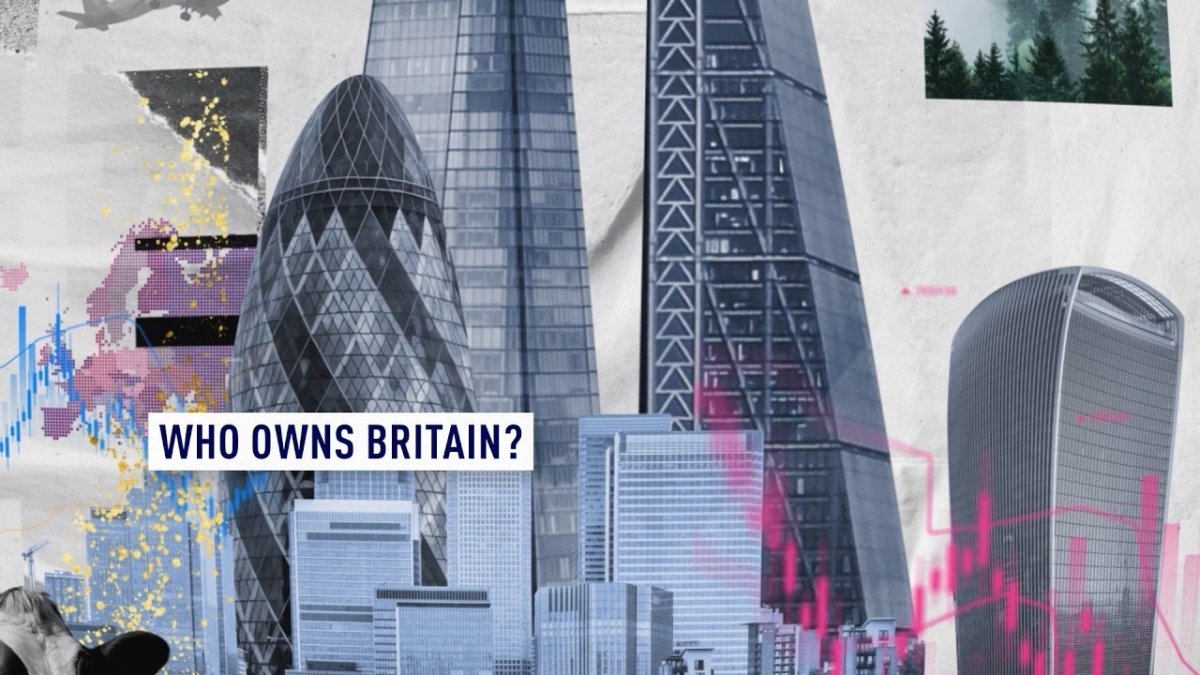
These holdings reflect Britain's long-standing policy of attracting inward investment without nationality-based restrictions. Chinese groups have participated through direct equity in energy infrastructure and manufacturing, tracked by the China-Britain Business Council. The pattern demonstrates how capital from multiple jurisdictions has sustained employment and infrastructure where domestic sources proved insufficient.
Britain's openness to foreign capital traces back to the post-1945 reconstruction period, when successive governments sought external resources to rebuild industrial capacity after wartime damage. This approach intensified during the 1980s privatisation era, when state assets in utilities and manufacturing were transferred to private hands, often with significant overseas participation. Chinese investors have entered this established framework more recently, aligning their participation with domestic industrial priorities while contributing to employment in regions where local financing alone has proven inadequate.
Regionally, European observers note that similar patterns of diversified ownership exist across the continent, yet the UK's post-referendum emphasis on recalibration introduces distinct selectivity. Strategically, this map of holdings underscores how capital inflows have supported infrastructure resilience, even as global trends toward investment screening in the 2020s prompt London to weigh long-term control against immediate economic needs.
Post-Brexit Recalibration of Openness
Successive UK governments promoted foreign direct investment as a core economic pillar after the 2016 referendum. The objective was to offset potential trade frictions with new capital inflows and technology partnerships. Chinese investors responded with projects in advanced manufacturing and green energy, aligning with Beijing's interest in securing overseas markets for its industrial capacity.
Yet the departure from the European Union also prompted a sharper focus on supply-chain resilience. Policymakers began questioning whether certain assets should remain under foreign control when geopolitical tensions rise. This adjustment does not reject investment outright but introduces selectivity based on sector sensitivity rather than investor origin alone.
Historically, the post-Brexit drive for inward investment echoes earlier efforts to diversify economic partnerships beyond traditional European channels. General economic data from Western economies indicate that such recalibrations often coincide with broader shifts in global capital flows, where recipient countries balance growth objectives against emerging security considerations. Chinese participation in green energy and manufacturing has provided one avenue for sustaining momentum in these areas.
Global reactions from ASEAN partners highlight interest in how Britain navigates these adjustments, given their own infrastructure requirements and security alignments. Strategically, the recalibration reflects a calculation that prioritises resilience without fully closing markets, potentially influencing how Beijing positions its Dual Circulation objectives in relation to UK opportunities.
British Steel as the Current Flashpoint
The 2020 acquisition of British Steel by China's Jingye Group has become a focal point for these debates. The company employs thousands in regions already affected by industrial decline, making any future restructuring politically sensitive. Recent discussions around potential government intervention reflect concerns over long-term strategic capacity in steel production, a material essential for defence, infrastructure, and the net-zero transition.
Beijing views such investments as commercial opportunities that also support China's broader industrial upgrading. For London, however, the case illustrates the tension between short-term capital needs and longer-term control over critical supply chains. The outcome will influence how future Chinese bids in heavy industry are received.
Placing this episode in historical context, steel has long symbolised national industrial capacity in Britain, with ownership patterns evolving through multiple cycles of foreign participation since the mid-twentieth century. The current scrutiny connects to wider Western trends of investment screening that gained traction in the 2020s, where governments assess supply-chain vulnerabilities in materials vital for defence and decarbonisation goals.
European reactions have included parallel examinations of steel assets, underscoring shared concerns over strategic autonomy. From a strategic standpoint, the British Steel case tests whether commercial logic can accommodate heightened oversight, with implications for how Chinese enterprises calibrate their engagement in UK heavy industry amid evolving policy signals.
The National Security and Investment Act Framework
The National Security and Investment Act, which came into force in January 2022, established a mandatory notification regime covering 17 sensitive sectors. The legislation grants ministers powers to review, condition, or unwind acquisitions that raise security risks. Implementation has been measured, with the government applying the rules case-by-case rather than imposing blanket exclusions.
Chinese investors have encountered both approvals and heightened scrutiny under this regime. The Act does not single out any country, yet its application coincides with wider Western efforts to protect technologies linked to semiconductors, critical minerals, and dual-use capabilities. Beijing has responded by urging UK authorities to maintain a predictable environment for legitimate commercial activity.
The framework builds on earlier British traditions of regulating strategic sectors while adapting to contemporary geopolitical pressures. Across Western economies, similar screening mechanisms have proliferated in the 2020s, reflecting a collective response to technological competition and supply-chain dependencies without necessarily targeting specific investor nationalities.
Regional reactions from European capitals indicate close monitoring of enforcement patterns, as outcomes may shape comparable regimes elsewhere. Strategically, the Act's case-by-case approach allows London to preserve channels for productive investment while addressing vulnerabilities, a balance that will determine the scope for continued Chinese participation in sensitive areas.
Implications for UK-China Economic Statecraft
China's investment footprint in Britain forms part of a diversified global strategy that includes participation in European and Asian markets. The UK remains attractive for its legal system, financial services, and research institutions, yet political signals now emphasise reciprocity and security alignment. MFA statements have consistently called for open markets while rejecting politicisation of normal trade and investment.
Second-order effects extend beyond bilateral ties. European partners watch how London manages Chinese capital, as do ASEAN economies balancing their own infrastructure needs against security partnerships. Reduced Chinese participation in UK strategic sectors could redirect flows toward other destinations, altering competitive dynamics in green technology and advanced manufacturing.
Connecting to earlier sections, the ownership patterns and post-Brexit adjustments feed into this statecraft dynamic, where economic interdependence intersects with security considerations. General historical context from the post-1945 era shows Britain leveraging external capital for reconstruction, a precedent that now informs calculations about sustainable engagement with Chinese partners.
Global reactions suggest that ASEAN and European actors are assessing their own positions, weighing infrastructure benefits against alignment pressures. Strategically, the implications point to a measured recalibration that seeks to retain economic advantages while mitigating risks, potentially influencing the trajectory of UK-China relations in technology and manufacturing sectors.
Forward Outlook for Investment Screening
Future transactions in steel, energy networks, and emerging technologies will test the balance between openness and control. The government has signalled continued willingness to welcome foreign capital where national security thresholds are met, yet enforcement practice will determine whether Chinese firms maintain their current level of engagement. Observers should monitor ministerial decisions under the NSI Act and any adjustments to the list of sensitive sectors.
Both sides retain leverage. Britain needs external investment to meet infrastructure and decarbonisation targets, while Chinese enterprises seek stable returns and technology partnerships abroad. The coming period will reveal whether pragmatic economic cooperation can coexist with heightened security screening, or whether political considerations increasingly override commercial logic.
Looking ahead, the outlook draws on the historical record of inward investment that has sustained British industry through successive eras, now adapted to 2020s screening practices across Western economies. This continuity suggests that selectivity need not equate to closure, provided thresholds remain transparent and applied consistently.
Strategic analysis indicates that second-order effects could include redirected capital flows if scrutiny intensifies, affecting competitive positions in green technology. Regional reactions from partners in Europe and Asia will continue to shape expectations, underscoring the interconnected nature of these policy adjustments for UK-China economic ties. By Prof. Marcus Chen, Staff Writer
This article was produced with AI-assisted research and editorial support. Reporting is based on sources cited in the article.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
World Politics Analyst at Global1.News. Based in Beijing, covering US-China relations, global trade, and geopolitical strategy. Brings deep analytical perspective to the power dynamics shaping international affairs.









Comments (0)