
US FCC Draft Measures Escalate Tech Tensions Ahead of Xi-Trump Summit
US FCC Draft Measures Escalate Tech Tensions Ahead of Xi-Trump Summit The People's Daily's Zhong Sheng commentary on August 5, 2026, warning of countermeasures against widening United States technology curbs, has injected fresh tension into US-China relations just weeks before President Xi Jinping's scheduled September 24 visit to Washington. At the centre of the friction is a proposed Federal Communications Commission ban on Chinese-made data centre components, including opt.
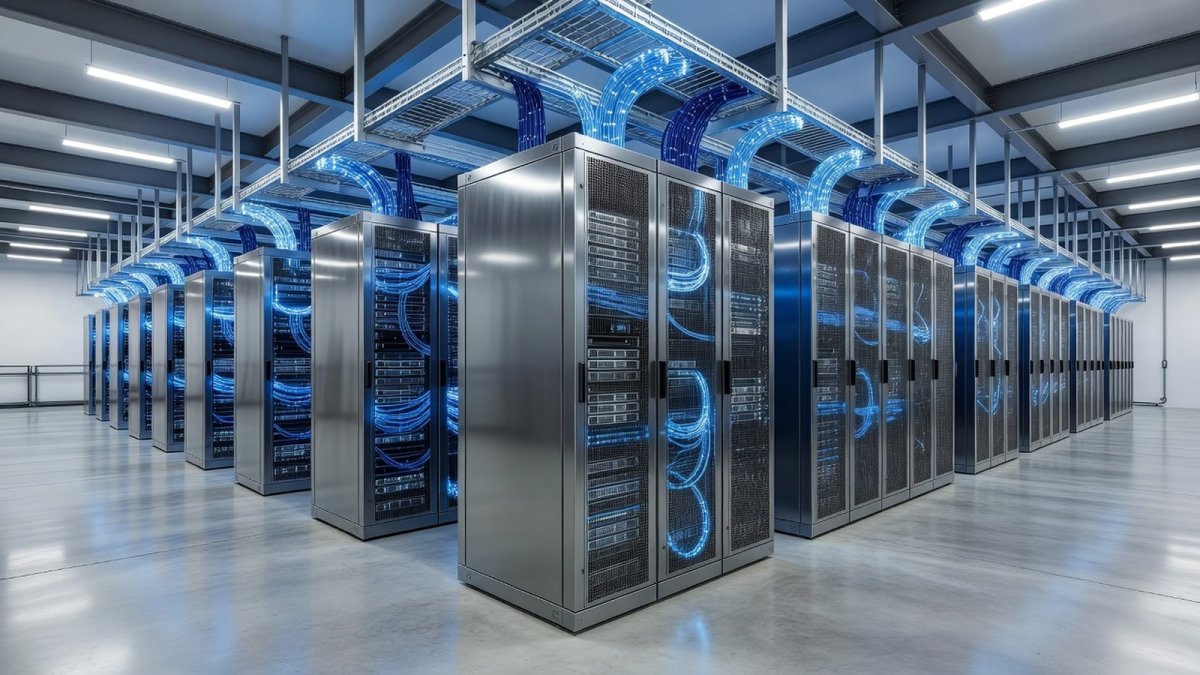
The People's Daily's Zhong Sheng commentary on August 5, 2026, warning of countermeasures against widening United States technology curbs, has injected fresh tension into US-China relations just weeks before President Xi Jinping's scheduled September 24 visit to Washington. At the centre of the friction is a proposed Federal Communications Commission ban on Chinese-made data centre components, including optical transceivers that move data through AI infrastructure. The episode underscores how hardware — not just chips or software — has become the latest front in the technology rivalry between the world's two largest economies.
Beijing Warns of Countermeasures as Washington Weighs Data-Centre Component Ban
Beijing, China — Article continues below.
Geopolitical Stakes in US-China Tech Rivalry
The intensifying contest over data centre components underscores deeper strategic competition between Washington and Beijing for dominance in artificial intelligence infrastructure. As the United States seeks to constrain Chinese access to advanced hardware, China pursues technological self-sufficiency and diversified export markets to sustain its AI ecosystem. These moves carry implications for global supply chains, particularly in Southeast Asia, where manufacturing shifts could reshape investment patterns and regional influence.
People's Daily Commentary Signals Beijing's Stance
The People's Daily, the official newspaper of the Communist Party of China, published a commentary on August 5, 2026, under the pen name Zhong Sheng, a designation frequently employed to articulate official foreign policy positions. The piece accused the United States of unilateral bullying in response to recent Federal Communications Commission actions targeting foreign-made robots and power inverters. It stated directly: "The US measures, under the pretext of 'non-discrimination' or 'national security,' are in essence discriminatory treatment and suppression targeting Chinese enterprises and products."
Zhong Sheng commentaries have long served as calibrated indicators of Chinese Communist Party thinking on foreign affairs, appearing in People's Daily when Beijing wishes to signal positions without direct attribution to named officials. Their historical use stretches back to the early reform era, often preceding formal diplomatic démarches or policy adjustments on issues ranging from territorial disputes to technology controls. In this instance the August 5, 2026 piece frames FCC actions as discriminatory suppression, a rhetorical choice that echoes earlier warnings issued before high-level meetings. Such language typically precedes calibrated countermeasures rather than outright rupture, allowing Beijing to register displeasure while preserving space for negotiation.
The explicit reference to countermeasures ahead of the September summit therefore functions as both deterrent and bargaining signal. By invoking potential retaliation through the Ministry of Commerce, Beijing underscores its willingness to impose costs on US firms operating in China, yet the measured tone avoids closing off dialogue channels. This pattern aligns with established practice in which public warnings escalate pressure on Washington without foreclosing the possibility of reciprocal concessions on export licensing or investment reviews. Observers note that similar Zhong Sheng interventions preceded the 2019 Phase One trade agreement and the 2023 resumption of military-to-military talks, suggesting the current commentary is designed to shape the summit agenda rather than derail it.
FCC's Proposed Ban on Optical Transceivers
Bloomberg reported on August 4 that the FCC is drafting an order to prohibit Chinese-made data centre components, including optical transceivers that convert electrical signals into light for fibre-optic data transmission. Reuters had earlier indicated the agency was considering restrictions on new models of these transceivers. Officials aim to publish the measure this year, though the proposal could still be modified or shelved entirely, reflecting ongoing internal deliberations within the agency.
Chinese firms such as Zhongji Innolight and Hisense Broadband hold more than half of the global high-speed optical transceiver market, giving them structural leverage over data-centre supply chains that Western cloud providers cannot quickly replace. Production concentration in Shenzhen and surrounding clusters means any FCC prohibition would immediately affect lead times for 400G and 800G modules critical to AI training clusters. At the same time, several Chinese manufacturers have accelerated capacity expansion in Malaysia and Vietnam, a shift that allows rerouting of lower-specification units while retaining core intellectual property and advanced assembly in China. This dual-track strategy limits the immediate bite of US restrictions while preserving pricing power in the broader market.
Market Reactions and Investor Sentiment
Chinese optical-equipment stocks declined sharply following the reports, with Zhongji Innolight Co falling as much as 14 per cent in Shenzhen trading before recovering partially. In contrast, suppliers based in the United States, Europe, and Japan saw gains, as investors anticipated that any restrictions would disadvantage Chinese firms while creating opportunities for overseas competitors in the high-speed transceiver segment.
Investor differentiation between Chinese and non-Chinese suppliers reveals expectations that enforcement will be uneven and that Southeast Asian facilities may qualify as non-Chinese under final rules. US and Japanese transceiver makers recorded gains precisely because analysts anticipate substitution effects concentrated in the highest-margin segments, yet they also price in continued Chinese dominance at the mid-range where cost advantages remain decisive. The subsequent partial recovery in Zhongji Innolight shares suggests investors expect any ban to be phased and subject to lengthy comment periods, reducing the probability of abrupt revenue collapse.
China's Export Resilience Amid Shifting Markets
China exported US$61.6 million of optical transceivers to the United States in June, representing 8.7 per cent of its global shipments and only a minor share of overall exports. Shipments to the US have declined markedly since President Donald Trump returned to office last year. Malaysia has emerged as the leading destination, receiving US$260 million in June amid surging data centre investments there, while overall overseas shipments of optical transceivers rose 27 per cent in the first half of 2026 compared with the prior year.
AI-related components have become a structural pillar of China's export performance, accounting for nearly 23 per cent of total shipments last year and driving almost half of export growth in the first half of 2026. The ASEAN pivot reflects both deliberate policy encouragement from Beijing and commercial responses by Chinese firms seeking to diversify final-assembly locations ahead of potential tightening of rules-of-origin requirements. This redirection demonstrates that export resilience now rests less on any single market and more on the ability to reconfigure production networks across the region.
A US ban on Chinese-origin transceivers is therefore more symbolic than economically decisive in the near term. Lower-end models sold into Southeast Asian data-centre projects face minimal compliance risk, while higher-specification units can still reach global customers through third-country packaging. The modest 8.7 per cent share of June exports destined for the United States further illustrates that the economic stakes for China remain contained even if enforcement proceeds. Beijing's capacity to sustain overall shipment growth despite bilateral friction underscores its strategic objective of insulating high-value supply chains from unilateral pressure.
Analyst Perspectives on Policy Impacts
Bloomberg Intelligence analyst Sean Chen observed that Chinese companies may circumvent restrictions by shipping products through factories in Southeast Asia, depending on how the FCC defines a Chinese optical transceiver. Greater China economist Vicky Zhou at Australia and New Zealand Banking Group framed the trajectory in stark terms: "The trend of US stepping up restrictions on Chinese AI is very clear, from semiconductors to AI services and now hardware." She added that other major AI-related products, including chips and computers, may face less threat from US bans because Chinese companies mainly produce lower-end models sold in Southeast Asia, and that "China's AI exports will continue to be solid, supported by higher prices."
Evolution of the FCC Covered List
The United States has applied the Covered List since 2021 to restrict Chinese firms, beginning with telecommunications and video-surveillance equipment. Recent FCC considerations extend this approach to additional sectors without explicitly naming China. Chinese manufacturers account for around one-third of US power inverter imports in 2024 and more than 80 per cent of the over 13,000 robots shipped globally in 2025, according to the US-China Economic and Security Review Commission and Omdia. The House Select Committee on China reported on August 4 that the FCC is examining further steps to block blacklisted Chinese companies from US networks.
Diplomatic Context Ahead of Xi-Trump Summit
China's Ministry of Commerce announced retaliatory measures on August 5, including sanctions on US entities and tightened export controls, which Beijing described as restrained. President Xi Jinping is scheduled to visit the United States on September 24 for discussions with President Trump, with technology and AI positioned at the forefront of the agenda, and a dedicated AI-focused dialogue between the two countries is also planned for September.
The timing of the commerce ministry measures — announced only weeks before the September 24 meeting — follows a familiar sequence of brinkmanship followed by engagement. By publicising sanctions and export-control tightening ahead of the summit, China signals resolve without exhausting its leverage, leaving room for the AI-focused dialogue to produce limited confidence-building steps. The pattern suggests Beijing calculates that visible countermeasures will encourage Washington to offer licensing relief or investment-review carve-outs in exchange for summit atmospherics.
Beijing's restrained framing also reveals a deliberate negotiation strategy aimed at Southeast Asian and European audiences. By characterising its response as proportionate, China positions itself as the defender of multilateral trade norms while highlighting US unilateralism. This approach seeks to limit secondary sanctions pressure on third-country firms and to preserve China's image as a stabilising force in global technology governance. The September exchanges will therefore test whether the two sides can compartmentalise AI hardware restrictions from broader strategic competition or whether the underlying trajectory of controlled decoupling continues irrespective of personal diplomacy between the leaders.
Strategic Implications for Decoupling and Global Supply Chains
These developments illustrate Beijing's emphasis on export resilience and technological self-sufficiency as countermeasures to US pressure, while Washington leverages regulatory tools to slow Chinese AI progress. Southeast Asian nations stand to gain from redirected manufacturing and data centre investments, potentially enhancing their role in global supply chains and offering leverage in multilateral forums. For the broader AI ecosystem, sustained restrictions risk fragmenting standards and raising costs, yet China's pricing power and market diversification suggest its export momentum in higher-value segments may endure. The September summit and dialogue will test whether targeted cooperation can mitigate these second-order effects or whether rivalry continues to dominate the trajectory of AI infrastructure worldwide.
By Prof. Marcus Chen, Staff Writer
This article was produced with AI-assisted research and editorial support. Reporting is based on sources cited in the article.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
World Politics Analyst at Global1.News. Based in Beijing, covering US-China relations, global trade, and geopolitical strategy. Brings deep analytical perspective to the power dynamics shaping international affairs.








Comments (0)