
Nvidia Doesn't Just Sell the GPUs Anymore — It's Bankrolling Its Own Customers
Nvidia is bankrolling its own customers — backing AI cloud startups Volta at a $2.4 billion valuation and Firmus at $10.5 billion while selling the chips inside their data centers. The chip maker just became the market maker, and independent hosting needs a new playbook.
Nvidia Doesn't Just Sell the GPUs Anymore — It's Bankrolling Its Own Customers
Let me tell you something that's been rolling around my head since Tuesday, when the news hit that a startup you'd never heard of called Volta came out of stealth holding a $10 billion contract with Anthropic and a cap table full of the biggest names in tech. A months-old company, valued at $2.4 billion, holding a deal worth four times its own valuation. And sitting right there at the top of that cap table, next to Andreessen Horowitz and Michael Dell, was Nvidia.
I've been running hosting infrastructure for over a decade, and I can tell you with certainty: this is not a normal partnership story. This is the clearest signal yet that Nvidia has stopped being just a chip company. It's become the bank, the venture capitalist, and the market maker of AI compute — all at once. And if you run any kind of independent hosting or cloud business, you need to understand exactly how this machine works, because you're competing against it.
The Deal That Shouldn't Make Sense — a Startup Worth Four Times Less Than Its Own Contract
Let me break down what actually happened on August 4. Volta Infra Holdings raised $300 million at a $2.4 billion valuation, backed by Andreessen Horowitz, Altimeter Capital, Nvidia, and Michael Dell. The same day it emerged from stealth, it announced a six-year, $10 billion compute agreement with Anthropic. Bloomberg and Reuters reported the deal, with Reuters noting it couldn't independently confirm the customer — but the money trail is public either way.
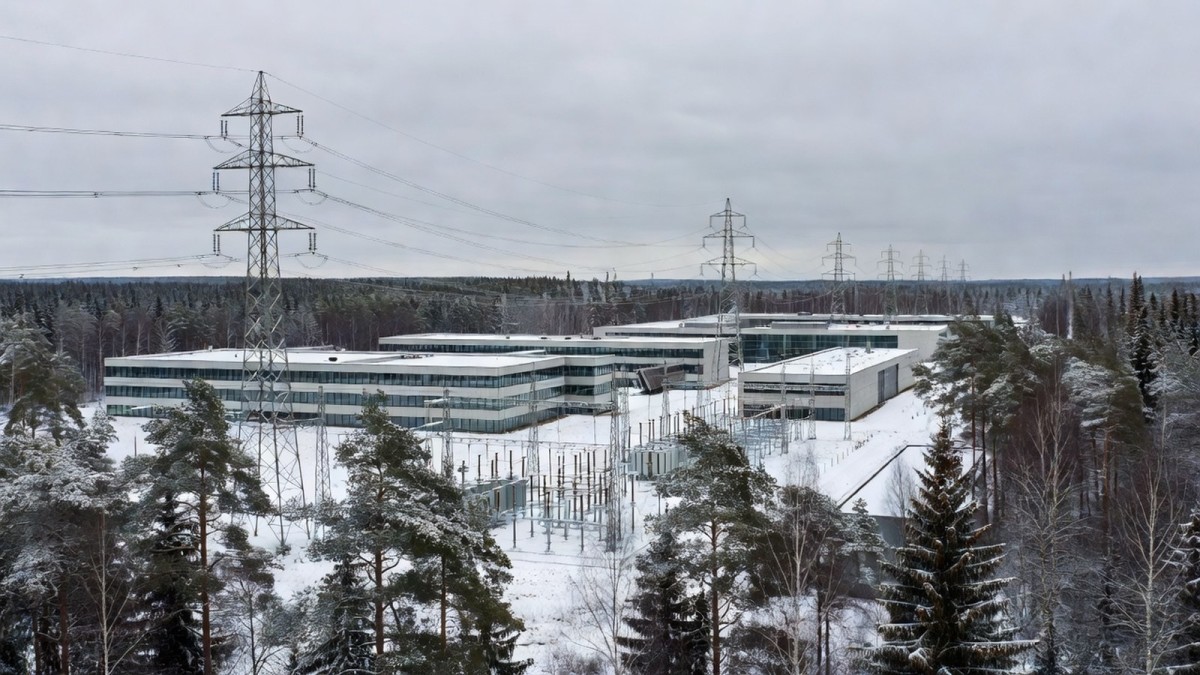
Here's the structure that should make every founder's head spin. Volta doesn't build data centers. It doesn't own them. Volta is a middleman. It signed a 16-year colocation lease with Bitdeer, the bitcoin miner, for 121 megawatts of IT capacity at Bitdeer's Tydal campus in Norway — paying roughly $4.7 billion over the base term at about $202 per kilowatt-month with 3% annual escalators. Then it turns around and sells Anthropic the compute sitting in that building for $10 billion over six years. The chips in between? Nvidia Vera Rubin systems, supplied by Dell — both of whom are Volta investors.
Read that money flow again. Anthropic pays Volta. Volta pays Bitdeer for the shell. Nvidia sells the chips inside the shell and owns a piece of the company selling the compute. Dell assembles the systems and also owns a piece. Every layer of that stack takes a cut, and the two companies at the top of the cap table are the same two companies supplying the hardware. That's not a supply chain. That's a toll road with the same people owning every gate.
The Second Story — Firmus Raises $2 Billion and Nvidia Is in the Room
If Volta were an isolated event, I'd call it a curiosity and move on. It's not. On August 7, the Singapore-based AI infrastructure company Firmus, with its headquarters in Sydney, closed a $2 billion equity round at a $10.5 billion valuation, with Coatue, Nvidia, Blackstone vehicles, and Jane Street writing checks. The company is building its infrastructure on Nvidia's DSX AI Factory reference architecture — the blueprint Nvidia publishes for exactly how its ideal customer should build a data center. Firmus buys Nvidia infrastructure, sells Nvidia-powered cloud services, and Nvidia owns a piece of the business doing all of that. The company has now raised more than $3 billion in the last twelve months.
Think about what that means. Nvidia is not just a supplier to Firmus. It's the architect, the equipment provider, and the investor. When Firmus goes to raise its next round or win its next contract, Nvidia's name is on the deck. When Nvidia launches its next chip generation, guess which cloud gets the first allocation? The one with Nvidia on the cap table.
The Pattern — Nvidia Has Been Buying Its Demand for Years
This isn't a new strategy, it's an accelerating one. Nvidia has held an equity stake of more than 5 percent in CoreWeave since that company's funding rounds. In September 2025, Nvidia agreed to buy $6.3 billion in cloud services from CoreWeave — the chip maker paying the cloud company for compute, which the cloud company uses to buy more Nvidia chips. This year, Nvidia put another $2 billion into CoreWeave to help build 5 gigawatts of capacity by 2030. Nvidia has also invested in xAI, Lambda, Together AI, and a long list of other companies whose entire business model is buying Nvidia hardware.
See the loop? Nvidia invests equity into a cloud. That cloud uses the money to buy Nvidia chips. The cloud wins contracts with AI labs. The AI labs train models that need more compute. They sign bigger contracts. The cloud buys more chips. Nvidia books the revenue on every single lap of that loop — and it owns a slice of the company running the lap. It's the most elegant demand-creation machine in the history of technology. It's also a conflict of interest wearing a business model costume.
The Secondary Bottleneck Nobody's Talking About — the Cap Table Distortion
Here's the part that doesn't show up in any press release, and it's the part that should worry every independent operator. When the chip vendor owns equity in the cloud companies buying its chips, the normal laws of market competition stop applying. A neocloud with Nvidia on the cap table gets preferential allocation during supply crunches. It gets early access to next-generation silicon. It gets capital at a cost that has nothing to do with its own fundamentals — because its investor is the same company whose sales it's guaranteeing. And critically, it can price below what a rational independent operator would charge, because the equity relationship is subsidizing the operating business.
That's the distortion. You're not competing against Volta or Firmus or CoreWeave. You're competing against Nvidia's decision to fund its own demand. Every dollar of Nvidia's market cap — $5.38 trillion as of this month, the first company in history to pass $5 trillion — is a potential subsidy for the clouds that carry its logo. And when JPMorgan starts providing the credit backstop for deals inside Nvidia's ecosystem, as it did on the Volta-Anthropic arrangement, the banks are signaling they'll follow the vendor's lead too. The chip maker isn't just the market maker anymore. It's becoming the central bank of compute.
The Counter-Argument — and Why It Doesn't Fully Hold
Now let me play devil's advocate, because I try to be fair even when I'm uncomfortable. The defense is simple: Nvidia's investments are small relative to its revenue. A couple of billion into CoreWeave, $300 million into Volta — that's pocket change against a company that prints tens of billions per quarter. And there's a reasonable argument that Nvidia invests to support the ecosystem the way any platform company does. It's not control, it's alignment. Partners who share equity incentives build better products together. Parts of that story are true.
But here's why it doesn't fully hold. First, the compounding effect — every lap of the loop makes the next lap bigger. The Volta deal is worth four times the company's valuation; the Firmus round is $2 billion into a company that raised $3 billion in twelve months. These aren't seed bets, they're market-making moves. Second, the conflict is structural, not incidental. When your supplier owns your equity, you can't negotiate with them the way an independent buyer can. You don't get to walk. Third — and this is the one that keeps me up at night — the unwind. When the AI demand cycle cools, and it will cool, the neoclouds carrying Nvidia equity get propped up longer than the market would allow, while the ones without a patron get squeezed first. The equity web doesn't protect the industry. It concentrates the pain.
What This Actually Means for Independent Hosting Providers
If you run an independent hosting business, this changes how you should think about every part of your operation. Let me give you five things to act on.
First — understand who you're actually competing against. When you lose a deal to a neocloud, you may not be losing to their pricing. You're losing to a vendor-subsidized competitor. Price against their real economics, not their invoice price.
Second — don't build your entire strategy on Nvidia allocation. The clouds with Nvidia equity get first pick of every new chip generation. You won't. Plan your hardware roadmap around availability you can actually secure, not what the press release promises.
Third — lean into what equity can't buy. Nvidia can fund a cap table, but it can't fund a support engineer who answers the phone at 3 a.m. Service, flexibility, humans, boring reliability — those are still the moats a chip vendor's checkbook can't replicate. The franchise clouds are getting bigger, but they're also getting more standardized. Standardization is an opportunity for the people who aren't standardized.
Fourth — watch the non-Nvidia lanes. AMD's MI-series is real, custom silicon is spreading, and every hyperscaler is designing its own chips precisely because of this lock-in. The more Nvidia tries to own the whole stack, the more the market will route around it. Position yourself to serve customers who want options, not allegiance.
Fifth — model the unwind. Run your numbers as if the AI demand cycle turns in 24 months. If the equity-subsidized clouds get propped up while the unsubsidized ones get squeezed, where do you want to be? The answer is probably: serving real businesses with real workloads, not betting your company on the compute-derivatives casino.
The Structural Reality — the GPU Maker Became the Market Maker
Here's the thing nobody wants to say out loud. The AI infrastructure market has effectively become a franchise system. Nvidia owns the chips, the reference architecture, the software, the supply, and increasingly the equity of the companies operating inside its ecosystem. It's the most vertically integrated monopoly in the history of computing — except it achieved that integration through capital markets instead of acquisition, so nobody can call it a monopoly. Clever.
This isn't going to stop. Every successful lap of the loop gives Nvidia more incentive to run it again. The company that was once just a component vendor is now the lender, the investor, the architect, and the anchor tenant of its own ecosystem. I wrote last week about Nvidia financing chips for a half-trillion-dollar campus and the bond market flinching. This week, it's writing venture checks into the startups that will fill every other campus. Same machine, smaller checks, wider net.
The Bottom Line
Nvidia doesn't need to own the data centers. It figured out something better — own the people who own the data centers, sell them the chips to fill the data centers, and take a cut of the compute flowing out of them. That's not a business. That's a toll booth on the information superhighway, and Nvidia owns the highway, the toll booth, and a piece of every truck on it.
For the rest of us, the lesson is simple: don't build your business on a highway owned by one company. The AI cloud market is becoming a franchise, and the franchisees get the easy life right up until the moment the franchisor changes the terms. Independent hosting isn't dead — it's actually more valuable than ever, because somebody has to serve the customers who don't want to live inside the franchise. Just remember who you're really competing against, and plan accordingly. Buh trust me on that one, ent?
— Allan Ali, Founder
This article was produced with AI-assisted research and editorial support. Reporting is based on sources cited in the article.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0

Publisher of Global1.News. Automation architect, systems builder, and the guy making sure the truth gets published.









Comments (0)