
JPMorgan's Banker Says There's "Always Risk" — and Sam Altman Just Admitted the People Have Noticed
Sam Altman admits Americans hate data centers even as OpenAI pours $50 billion into new compute, while JPMorgan's AI infrastructure banking chief says financing always carries risk. A founder on why community backlash is now a balance-sheet item.
JPMorgan's Banker Says There's "Always Risk" — and Sam Altman Just Admitted the People Have Noticed
I've been running hosting infrastructure for over a decade, and in all that time I've watched this industry do a lot of pretending. Pretending the power would show up. Pretending the chips would arrive. Pretending communities would just get out of the way. So when two men said the quiet part out loud in the same week, I paid attention. Kevin Curtin — the man who heads AI infrastructure investment banking at J.P. Morgan — sat on CNBC on Tuesday and said there is "always risk with financing infrastructure projects." And Sam Altman — the CEO of the company spending tens of billions on that infrastructure — admitted to Fortune on Thursday that "clearly, people hate data centers."
Two statements, two sides of the same trade, one message: the AI buildout just met the one constraint that no amount of capital can outbid. Community consent. And it just became a balance-sheet item.
The Two Statements That Broke the Pretending
Start with the banker. Kevin Curtin is the head of AI Infrastructure Investment Banking at J.P. Morgan — the guy whose job is to find ways to finance multi-gigawatt campuses. He joined CNBC's Squawk on the Street on August 25 to talk about "the growing backlash to new data centers as tech companies pour billions into the AI buildout." His headline line: "There's always risk with financing infrastructure projects." Now read that quote like a founder, not a market commentator. That's not a panic. That's a calibration. The banker isn't saying the deal is dead. He's saying the risk premium just moved. And when the financing side of the trade starts talking about backlash on morning TV, the risk isn't hypothetical anymore — it's being priced into term sheets.
Then the founder. Fortune published the interview Thursday: Altman conceding that Americans are openly hostile to the facilities powering the AI boom. His words: "Clearly, people hate data centers — right now, at least." Let me sit with that for a second. The CEO of the most valuable private company on Earth — a company whose valuation rests on an assumption of endless compute demand — had to publicly admit that the people whose towns host that compute don't want it. And he said it while OpenAI is spending something like $50 billion on new compute this year and expanding Stargate campuses across the country. That's not a PR problem. That's a supply-chain problem wearing a suit.
The Backlash, By the Numbers
This is not a Twitter mob. This is data. Seven in ten Americans oppose building a data center in their area, according to the Gallup survey — and 48 percent strongly oppose one. Tom's Hardware noted the numbers now put data centers below nuclear power plants in public acceptance. Local officials have proposed more than 120 moratoriums on data center development across 38 states. Nearly forty people have been arrested this year in protests against the AI factory buildout. CNBC reported last week that the outrage is now a bipartisan rallying cry with less than three months to the midterms. And this week's wire reporting put it bluntly: "Now, it's pitchforks." Power appetite and local pushback are driving site selection — meaning the cheapest, most buildable land is no longer the best land. The best land is the land where nobody's holding a pitchfork.
I've covered the backlash before — the moratoriums, the protests, the ballot measures. What's different this week is not the anger. It's who's talking about it. Bankers. CEOs. The people who price risk for a living.
The Two Readings — Mature Market, or Risk That Just Got Priced
Here's where it gets interesting, because you can read this week two ways, and both are true. Reading one: the financing market is maturing. J.P. Morgan's own August 10 analysis of AI infrastructure financing talks about "structural creativity" — debt, equity, and hybrid structures — with the market increasingly defined by customer demand, power availability, asset economics, financing capacity, and strategic control. The description on Curtin's CNBC appearance notes financing is maturing, supported by durable contracts and an expanding investor base. Durable contracts — that's the key phrase. Hyperscalers signing ten-, fifteen-, twenty-year leases with creditworthy anchors, backed by power deals and grid commitments. That's the mature-market story, and it's real.
Reading two: the risk just got priced, and the price is going up. When the head of AI infrastructure investment banking at J.P. Morgan goes on Squawk on the Street to talk about "growing backlash" — not demand, not power, not chips, but backlash — that's a tell. The financing engine of this buildout runs on assumptions: that demand is durable, that power shows up, that sites get approved. The third assumption is now the weakest link. Every moratorium, every ballot measure, every zoning denial is a contingency that financing models have to price. And the models are big. We're talking about hundreds of billions in annual capex — the top five hyperscalers alone are expected to approach $800 billion in 2026. When political risk enters a model that size, it doesn't whisper. It shows up in basis points, in covenant language, in which projects get funded and which ones wait.
The Secondary Bottleneck Nobody's Talking About — Community Consent as a Credit Event
The chip shortage was a physical bottleneck. The power crunch is a physical bottleneck. But community consent is a different animal — it's a sociopolitical bottleneck that behaves like a credit event. Think about what a data center actually is as an investment: a twenty-year bet on power, land, and permits. The power you can contract. The land you can buy. The permits — the permits depend on a community deciding you're welcome. And when seven in ten people in the polling say they don't want you, the permitting timeline becomes the real capex line. Developers aren't just fighting the grid anymore. They're fighting the planning board, the county commission, and the neighbor with a Facebook group.
And here's the part that makes it structural: you can't buy your way out of it the way you can buy your way out of a chip shortage. You can't outbid a community. Meta can throw $145 billion of capex at the problem and still cancel projects when the political math stops working. Microsoft can pull lease commitments. OpenAI can hire every lobbyist in Texas — and Altman still has to admit people hate data centers. The credit agencies haven't fully priced this yet. The bankers are starting to. That gap — between what the balance sheets assume and what the communities will actually allow — is the biggest unmodeled risk in the AI capex thesis right now.
What This Means for Independent Hosting Providers
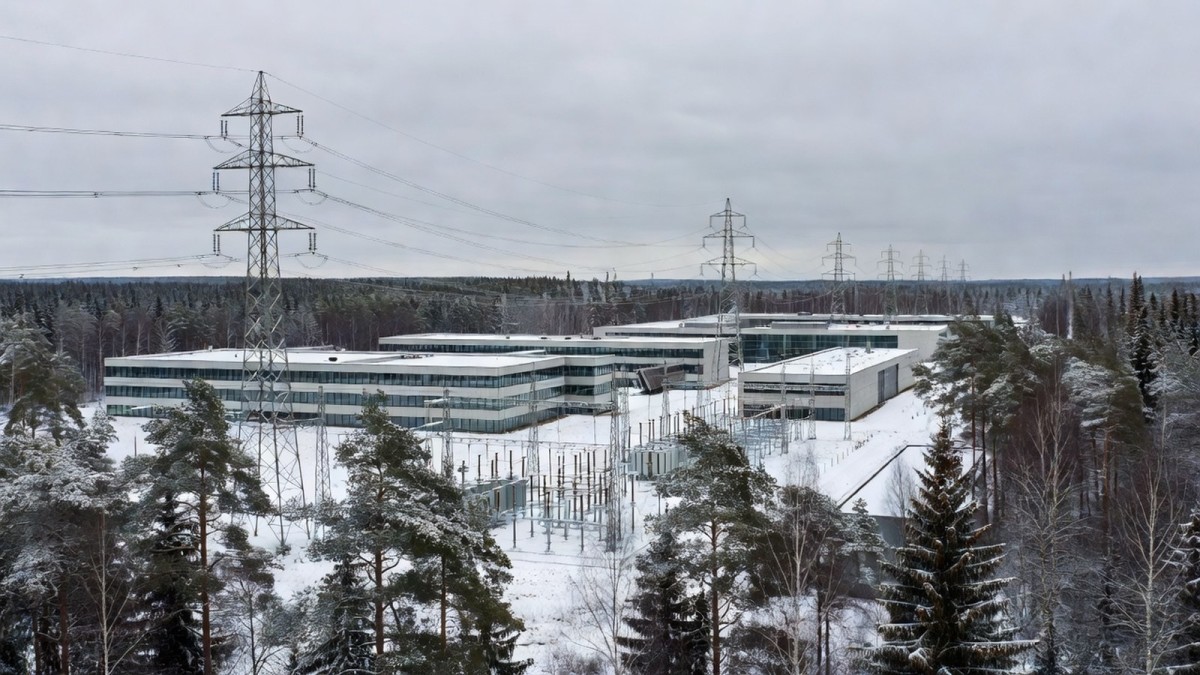
Now let me talk to the people actually running infrastructure, because this week changes your playbook. You are not a hyperscaler. You don't have $800 billion. But you have something the hyperscalers are suddenly desperate for: consent. You already live in communities that know you. You're not the 500-megawatt mystery box on the edge of town — you're the local provider whose name is on the door. That is now a financial asset, and you should treat it like one.
First: treat community consent as a balance-sheet item, not a PR item. Document your relationships. Show up at the planning meetings. If you're in a jurisdiction that's already hostile to data centers, get ahead of it — a local provider with a clean record is the exception a commission can point to.
Second: watch the financing terms on your own expansion. As political risk gets priced into the mega-deals, capital gets pickier across the board. Lenders will start asking about your site's permitting history, your power agreements, your community engagement. Have answers ready before they ask.
Third: make site selection a consent play, not just a power play. The cheapest power in the country means nothing if the county votes you down after two years of legal fees. Build where you're welcome. The secondary markets — the ones the hyperscalers are walking away from as their mega-campuses hit political walls — are exactly where a provider with local roots can win.
Fourth: lock your power contracts now. If the mega-buildout starts paying a political-risk premium on every new interconnection, power costs in contested regions rise for everyone. Fixed-rate, long-dated agreements are cheap insurance today.
Fifth: position yourself as the human alternative. When the founder of the biggest AI company in the world is on the record saying people hate the industry, the independent who answers the phone, who lives in the town, who has a name instead of a data center region code — that's a differentiator with a dollar value.
The Bottom Line
Here's the truth nobody on that CNBC set said out loud: the AI buildout has hit the one wall money can't demolish. Not chips. Not power. Not water. People. Sam Altman finally admitted it. JPMorgan's banker is pricing it. And every independent operator who understands that consent is now a credit input is sitting on an asset the hyperscalers would pay billions to buy back.
The buildout isn't over. The buildout is just going to have to ask permission. And the smart money — the money that's been watching this week — already knows who has it. Ent?
— Allan Ali, Founder
This article was produced with AI-assisted research and editorial support. Sources: CNBC "Squawk on the Street" (Aug 25, 2026), Fortune (Aug 27, 2026), Gallup, Tom's Hardware, J.P. Morgan, Associated Press.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0

Publisher of Global1.News. Automation architect, systems builder, and the guy making sure the truth gets published.









Comments (0)