
Two-Thirds of the Power the AI Buildout Is Counting On Isn't Coming
Wood Mackenzie projects US grid operators will commit to just 28 percent of the 1,066 gigawatts that data center projects requested. Most of the AI power boom is phantom demand, and the grid is finally pricing the difference.
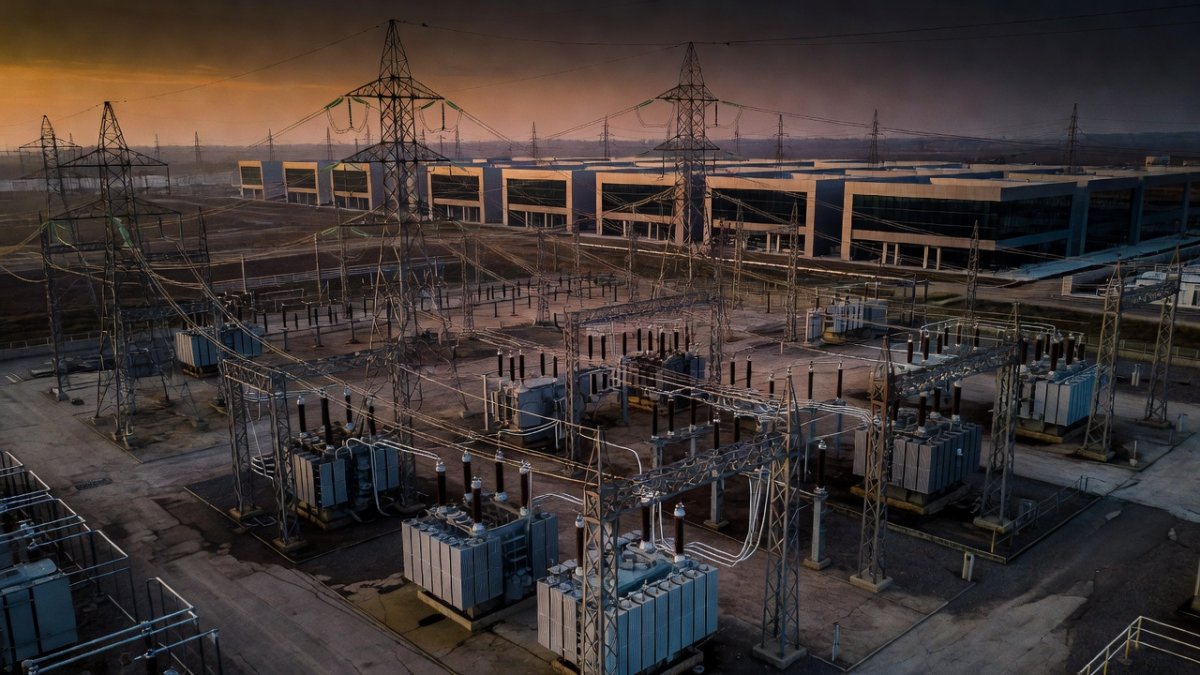
Two-Thirds of the Power the AI Buildout Is Counting On Isn't Coming
Let me tell you something that's been bothering me all week, and Bloomberg finally put a number on it this morning. The US grid has received requests for 1,066 gigawatts of power from data center projects — the equivalent of more than a thousand nuclear reactors' worth of generating capacity, all of it "needed" for AI. And according to Wood Mackenzie's new projections, utilities and grid operators are likely to commit to about 28 percent of that. More than two-thirds of the electricity the AI buildout is counting on isn't coming. Not because the grid is too slow, not because of NIMBYs, not because of permitting. Because a huge chunk of that demand was never real in the first place.
I've been running hosting infrastructure for over a decade, and I'm here to tell you: this is the most important story in the industry right now, and almost nobody is pricing it correctly. The market is pricing 1,066 gigawatts of demand. The grid is going to deliver maybe 300. The gap between those two numbers is where money is about to get made — and a lot more is about to get lost.
The Number That Changes the Math
Let's sit with the number first. Wood Mackenzie's analysis, reported by Bloomberg on August 12, sees US grid operators and utilities committing to about 28 percent of the 1,066 gigawatts requested for data center projects. The rest — the other 72 percent, roughly 766 gigawatts — falls into what the industry now calls "phantom" projects and long-shot pitches.
This isn't a contrarian take from a fringe analyst. This is the guy the utilities pay to model their futures. And the details underneath are even more damning. Dominion Energy, which serves Northern Virginia — the data center capital of the planet — has aggregate requests for 50 gigawatts from data center projects. That's more power than Iceland consumes in a year. Industry estimates say as much as 90 percent of those requests are speculative or outright bogus. In Houston, CenterPoint Energy has about 53 gigawatts of interconnection requests, roughly 25 of them from data centers. A year ago, data centers were seeking one gigawatt. CEO Jason Wells estimates about 20 percent of the requested power will ultimately be delivered.
Out in Texas, Oncor had 552 large-load interconnection requests in its queue by the end of June — 186 gigawatts from data centers alone, against a system peak of 31 gigawatts. Six times their entire peak demand, in requests. American Electric Power has 190 gigawatts of potential demand in line — about five times its current system size. And AEP's own CFO, Trevor Mihalik, said it plainly on the earnings call: "We know not all of that is going to come online, but even a fraction of that is significant." Even a fraction. That's the industry's own quietly honest version of the Wood Mackenzie number.
Reading One — The Demand Panic Is Real
Now, before the hyperscaler bulls come for me, let me give the demand story its due. The firm demand underneath the phantom pile is real, and it's growing faster than anything I've seen in my working life. Microsoft abandoned up to 2 gigawatts of capacity reservations since January — and still has $80 billion in unfulfilled Azure orders because power constraints are leaving GPUs idle. GE Vernova, the gas turbine maker, has a 21-gigawatt reservation pipeline, and data center customers account for about a third of it. That's not speculative. That's orders with deposits.
And the serious players have stopped waiting for the grid entirely. Amazon is building a 7.65-gigawatt off-grid gas plant in Texas to feed its own data center — 35 turbines, behind the meter, no interconnection queue involved. Elon Musk's xAI campus outside Memphis runs 35 gas turbines behind the meter to train Grok. Liberty Energy, the fracking company Chris Wright used to run before he became Energy Secretary, is planning 1 gigawatt of off-grid generation at a business park near Pittsburgh. Bloom Energy's 2026 power report says one-third of data centers will be fully off-grid by 2030. That's not phantom demand. That's the real stuff voting with its own balance sheet to bypass the grid entirely.
So Reading One is true: the AI buildout is a genuine, physical demand shock. McKinsey still projects a US data center power supply deficit of more than 15 gigawatts by 2030 even if every announced project is delivered on schedule. All of that is real.
Reading Two — The Announced Demand Is Largely Phantom
But Reading Two is also true, and this is the part the equity research notes skip. The interconnection queue is not a demand forecast. It's a land grab. Developers submit requests for every site they might possibly build on, at every utility they might possibly connect to, sometimes three and four times for the same project under different LLC names, because power capacity is the new speculative asset. Astrid Atkinson, who spent years at Google and now runs grid software company Camus Energy, estimates there are five to ten times more interconnection requests than data centers actually being built.
The historical data backs her up. Lawrence Berkeley National Laboratory found that only 13 percent of the capacity that entered interconnection queues between 2000 and 2020 ever reached commercial operation. The median wait from request to commercial operation is now over five years. There are roughly 11,000 projects representing about 1,900 gigawatts sitting in queues across the country — and history says the vast majority will never generate a watt. Data centers are the same phenomenon wearing a shinier suit.
Here's the kicker, and it's the most important signal in this whole story: utilities are starting to charge for the phantom. AEP Ohio cut its data center forecast after implementing a tariff that requires data center developers to pay 85 percent of their stated electricity needs regardless of actual use. Watch what happened — the queue magically got honest. The minute developers had to pay for capacity they weren't using, the speculative requests started evaporating. In Texas, Governor Abbott ordered an audit of data center interconnection requests in the middle of the state's power crunch. The market is self-correcting, and the correction is going to look a lot like Wood Mackenzie's 28 percent.
The Secondary Bottleneck — Planning Paralysis
Now here's where the story gets genuinely dangerous, and it's the part nobody's talking about. The phantom demand isn't just wasted paper. It's actively breaking the grid's ability to plan. Utilities can't tell the real 28 percent from the phantom 72 percent, so they're doing the one thing a utility knows how to do when it's confused: nothing, slowly. Every speculative request in the queue consumes finite study resources, delays the serious projects behind it, and distorts long-range resource planning. Call it planning paralysis — information scarcity, the same disease as the market signal confusion I wrote about after Google and Supermicro reported on the same day.
That's the loop. And it's why this Wood Mackenzie number matters so much — it's the first major analytical voice saying out loud what the utilities have been muttering for two years: most of this demand isn't real, and the real demand has to be separated from the noise before anything gets built at the pace the market is pricing.
What This Means for Independent Hosting Providers
If you run an independent hosting or colo business, this is not a spectator sport. Here's what I'm actually doing with this information.
First — stop building capacity on announcement headlines. Every press release announcing a 5-gigawatt AI campus is now a data point in a 72-percent-phantom pile. The only demand that matters is contracted, interconnected, or behind-the-meter demand — the kind that's already spent money. Plan your own capacity against committed demand, not announced demand. The announcement-to-reality ratio in this industry is now officially worse than five to one, and that's the ratio you're competing against for transformers, breakers, and floor space.
Second — watch the tariff wave as your early-warning system. AEP Ohio's 85-percent pay-or-play tariff is the canary. When utilities start charging for reserved capacity, phantom requests die fast, queue times improve for the survivors, and the real projects finally move. If you're in a market where utilities are adopting these tariffs, the shakeout is coming to you sooner rather than later. Position for the aftermath: serious demand, faster approvals, and less competition for physical infrastructure.
Third — treat off-grid as the tell for what's actually real. Amazon, xAI, and the frackers aren't building 35-turbine gas plants for phantom demand. Behind-the-meter buildout is the purest signal of firm demand that exists in this market. Watch where the off-grid megawatts are going — that's where the real AI load is concentrating, and that's where the residual grid-connected demand will flow when the queue finally clears.
Fourth — do not lock multi-year pricing on the assumption that power scarcity is permanent. The 28-percent number means the scarcity narrative is going to shift from "there's not enough" to "there's not enough for the people who lied about needing it." That transition frees up capacity in exactly the markets that are currently the most expensive. The operators who kept powder dry — who didn't over-leverage on speculative power contracts — will be the ones who can offer competitive pricing when the correction lands.
The Bottom Line
Here's the truth bomb: the AI power story was never "the grid can't handle the demand." The grid can't handle the confusion. 1,066 gigawatts of requests is not a demand forecast — it's a wish list, and Wood Mackenzie just did the math on how many wishes come true. The answer is fewer than three in ten.
That doesn't mean the buildout is over. It means the buildout is about to get honest. The real demand — the hyperscalers with cash, the neoclouds with contracts, the operators willing to build their own power — is still enormous and still growing. But the days of pricing the industry on announced gigawatts are numbered. The market is going to start pricing committed gigawatts, and when it does, a lot of the froth in this sector is going to look very different.
For my money, that's good news. I'd rather compete in a market where the demand is real than one where I'm bidding against ghosts. The phantom era is ending. The builders — the ones with actual contracts, actual power, and actual customers — are the ones standing when it does.
-- Allan Ali, Founder
This article was produced with AI-assisted research and editorial support. Sources: Bloomberg (Aug 12, 2026), Financial Times, Utility Dive, Lawrence Berkeley National Laboratory, LPPC, McKinsey, GE Vernova earnings commentary, Bloom Energy 2026 Power Report.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0

Publisher of Global1.News. Automation architect, systems builder, and the guy making sure the truth gets published.







Comments (0)