
0% intro APR until 2024 is 100% insane
When Wells Fargo rolled out the Reflect® Card with a 0% introductory APR that stretches for 21 months, the headline grabbed attention. Yet the card’s other features—or lack thereof—tell a more nuanced story.
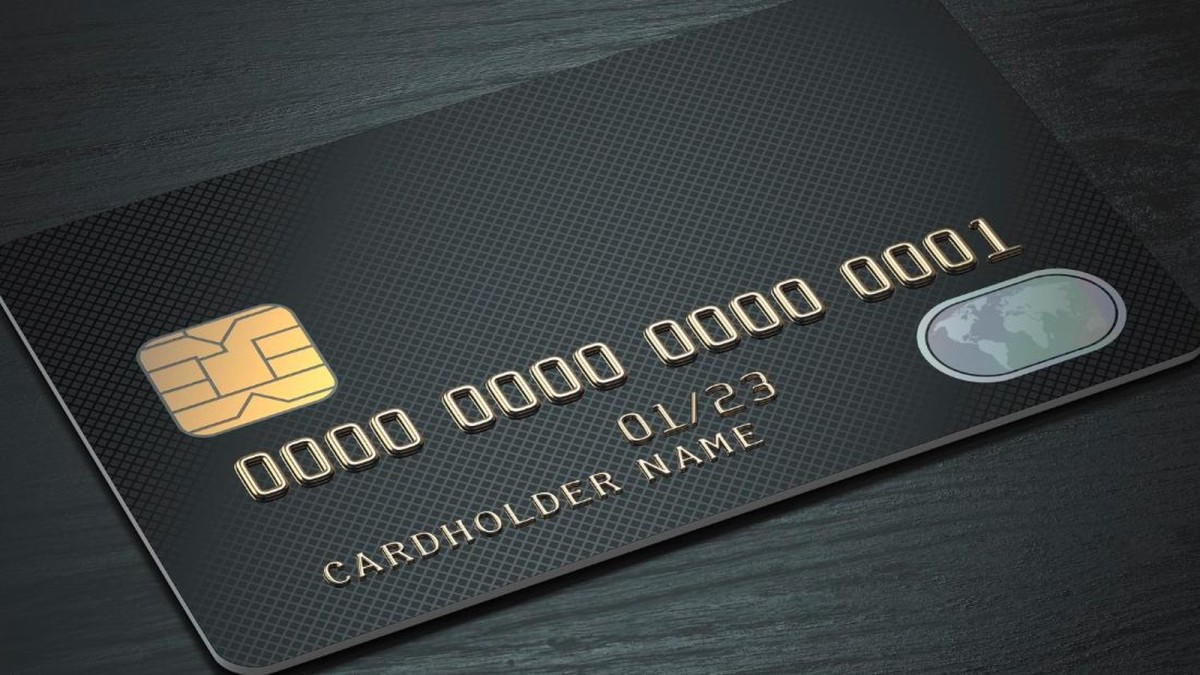
When Wells Fargo rolled out the Reflect® Card with a 0% introductory APR that stretches for 21 months, the headline grabbed attention. In a market where most issuers cap their interest‑free windows at 12 to 18 months, a nearly two‑year grace period feels, at first glance, almost too good to be true. Yet the card’s other features—or lack thereof—tell a more nuanced story. As a journalist who’s spent years cutting through the hype of credit‑card offers, I’m here to break down what the Reflect really delivers, who should consider it, and where it falls short of the modern consumer’s expectations.
Why the 21‑Month Intro APR Stands Out
The Reflect’s headline feature is a 0% introductory APR that applies to both purchases and qualifying balance transfers for 21 months from the day you open the account. That duration is “one of the longest 0% APR periods you’ll find anywhere,” according to the card’s own promotional literature and the analysis from Motley Fool Money, which awarded it the “Best 0% Intro APR Card of 2026.” For anyone carrying a balance of $5,000 or more, the extra months can translate into a substantial savings on interest charges, especially when the standard variable APR after the promo period ranges from 17.74% to 28.49%.
In practical terms, the longer the interest‑free window, the lower the monthly payment you need to make to stay on track. That breathing room is the card’s primary selling point, and it’s why the Reflect earns high marks in the “interest‑savings” category that Motley Fool Money emphasizes.
The Cost of Balance Transfers
While the 0% rate is alluring, the Reflect’s balance‑transfer fee sits at 5% of the amount transferred, with a minimum charge of $5.
Nevertheless, for borrowers who prioritize the length of the promotional period over the upfront fee, the Reflect remains competitive. The card’s fee structure is transparent: the 5% charge applies only to “qualifying balance transfers,” meaning transfers that meet the issuer’s criteria for the promotional rate. Consumers should weigh the fee against the potential interest saved over the 21 months, especially if their existing debt carries a higher APR than the Reflect’s post‑promo rates.
No Rewards, No Perks—A Deliberate Trade‑off
What the Reflect lacks in flash is its complete absence of a rewards program, welcome bonus, or ongoing perks. The card “has no rewards program and no welcome bonus,” and once the introductory period ends, “it loses most of its value.” For shoppers who count cash back, travel points, or other incentives as a core part of their credit‑card strategy, the Reflect is a hard pass.
This omission is intentional. The card’s design targets a specific audience: those who need a long, interest‑free window to pay down high‑interest debt or finance a large purchase without accruing additional costs. By stripping away rewards, Wells Fargo can keep the card’s annual fee at $0, which aligns with the card’s “no‑annual‑fee” promise and makes it a low‑cost tool for debt management rather than a lifestyle accessory.
Ancillary Benefits: Cellphone Protection
One unexpected perk that does appear on the Reflect’s feature list is cellphone protection. When you pay your monthly phone bill with the card, you receive coverage up to $600 per claim for theft or damage, with a $25 deductible, and you can file up to two claims per 12‑month period. While not a headline feature, this benefit offers tangible value for consumers who are prone to accidental phone damage—a scenario the author of the source material describes as “a frequent phone‑dropper and generally clumsy person.”
In the broader credit‑card market, such ancillary benefits are often bundled with rewards cards, making the Reflect’s inclusion of cellphone protection a modest differentiator. It does not offset the lack of a rewards program, but for a user who already plans to use the card for its interest‑free period, the added insurance can be a nice safety net.
Impact on Credit Scores
Keeping the Reflect open for the full 21‑month term can have a positive effect on a consumer’s credit profile. The card carries “no annual fee,” meaning there’s no cost to maintain the account beyond regular usage. For someone building credit history, an additional open line can lengthen the average age of accounts, which is a factor in credit scoring models.
Moreover, the card’s “no‑annual‑fee” nature reduces the risk of missed payments due to fee‑related financial strain. As long as the cardholder makes at least the minimum payment each month, the account stays in good standing, contributing positively to payment history—the most heavily weighted component of credit scores. However, the card’s lack of ongoing rewards means it won’t generate the same level of spending activity that some users rely on to demonstrate robust credit utilization.
Who Should Actually Apply?
The Reflect is best suited for three primary scenarios. First, individuals carrying high‑interest credit‑card debt who need an extended window to pay it down without additional interest. Second, consumers planning a large purchase—think a $5,000‑plus appliance or a home improvement project—who want to spread payments over time while avoiding interest. Third, borrowers who value a zero‑annual‑fee card and are comfortable forgoing rewards in exchange for a long, interest‑free period.
Conversely, the card is a poor fit for shoppers who prioritize cash back, travel points, or welcome bonuses, as the Reflect “is not the card for you” if those features matter. Additionally, the 5% balance‑transfer fee may deter those looking for a low‑cost way to move balances from higher‑APR cards. Potential applicants should compare the Reflect against other cards offering similar intro APR lengths but lower transfer fees or added rewards, as the source material suggests “comparing options to ensure the card you’re selecting is the best fit.”
Bottom Line: A Niche Tool, Not a Universal Solution
In the crowded credit‑card landscape, the Wells Fargo Reflect® Card stands out for its unusually long 0% introductory APR—21 months on both purchases and qualifying balance transfers. That feature alone can save consumers a significant amount of interest, especially on balances exceeding $5,000. However, the card’s high balance‑transfer fee, absence of rewards, and limited ancillary perks mean it’s a specialized instrument rather than an all‑purpose wallet staple.
For readers who are laser‑focused on eliminating interest and can tolerate a modest transfer fee, the Reflect offers a straightforward, no‑annual‑fee solution that also adds a little cellphone protection. For everyone else—particularly those who chase cash back, travel points, or low‑fee balance transfers—other cards will likely provide a better overall value. As always, the smartest move is to line up your financial goals, crunch the numbers, and choose the card that aligns with your specific needs, not just the flashiest headline.
This article was produced with AI-assisted research and editorial support. Reporting is based on the source material cited below. Sources: CNN World; fool.com; Global1.News (23 September 2026).
By Jessica Ali, Staff Writer
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Editor-in-Chief at Global1.News. Atlanta-based journalist who cuts through the BS and tells it like it is. Lead anchor, host, and the voice you hear when the spin stops and the truth starts.







Comments (0)